Never Short a Dull Market
- After last week’s full menu of inflation news, all of it of the hot variety, this week is slated to be less eventful, at least that’s the expectation. The economic calendar is light and what is on offer is limited to second- and third-tier releases. In addition, the Fed has entered the pre-FOMC isolation booth so don’t expect any headlines from the folks that vote on monetary policy. That leaves us to watch the action in AI-related equities and of course any geo-political headlines that may arise. The following week offers up the FOMC rate decision but with the market convinced the Fed will wait until December the pickings for the balance of October may be thin. Of course, the one line of market wisdom that comes to mind is “never short a dull market” so there is that. In any event, we do highlight the few items on tap this week for your brief reading pleasure. Currently, the 10yr is yielding 5.09%, down 1bp, while the 2yr is yielding 4.73%, unchanged on the day.
- Adding more insult to injury in this week’s meager offerings, the one data highlight doesn’t arrive until Friday with the release of the preliminary S&P Global PMI numbers for October. Recall last month the preliminary results were uniformly strong and that began the latest wave of Treasury selling with expectations of an October rate hike. My how the tone changed in the subsequent weeks. The September Manufacturing PMI printed at 55.9, Services at 58.8, and Composite at 58.4. With 50 being the dividing line between a contracting and expanding sector the September results were strongly expansionary and that expectation is for continued expansionary readings but with slightly less strength than in September.
- Tomorrow brings the weekly ADP Pulse Report of private sector job growth. Last week the report found 24,750 new private sector jobs for the week ending September 26th. The figure is a four-week average to smooth monthly volatility, but the result was the fourth straight week of 20,000 plus in jobs indicating a monthly figure between 80 and 100 thousand. The September ADP monthly figure was 90,000 private sector jobs so the latest data points to a similar result when October figures are released, meaning employment continues with little to indicate an imminent slowdown.
- Also on Tuesday, September Housing Starts and permits will be issued to give us the latest read on the moribund housing market. Housing starts are expected at 1.310 million annualized vs. 1.275 million in August for a 2.3% increase in starts. Building permits are expected at 1.385 million vs. 1.403 million the prior month for a -1.7% dip in permits. Permits are usually the more reliable estimate of housing activity as the starts figure can often be hamstrung by weather issues in one part of the country or another. In any event, with mortgage rates sporting a 7-handle and home values holding firm, wage gains mired at 3% YoY, the housing market continues to muddle along without a near-term catalyst to spur activity higher.
- Pending Home Sales for September will also be released tomorrow and as a more real-time view of the market sales are expected to increase a slight 0.5% for the month vs. 0.3% in August. The year-over-year change in pending sales for August was down -4.9%, which is yet another indicator of the difficult environment for housing at the present time, and like we mentioned above, there’s not an obvious catalyst on the horizon to boost the market. So, economic growth looks to be driven by the ongoing AI demand and healthcare hiring.
Odds are High for a Hike at the December FOMC Meeting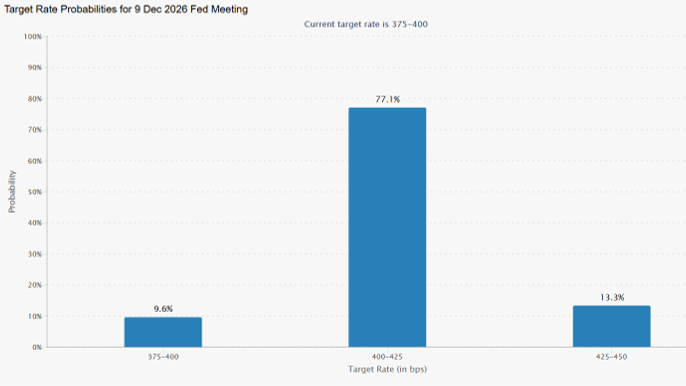 Source: CME Group
S&P Global PMI Activity – The September Surge Helped Ignite the Yield Push Early in the Month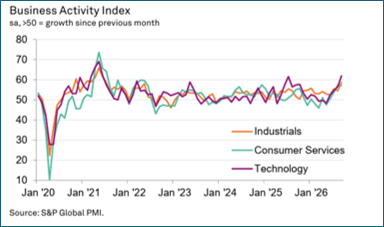 Source: S&P Global
S&P Global PMI Price Index – The September Price Spike Also Boosted Yields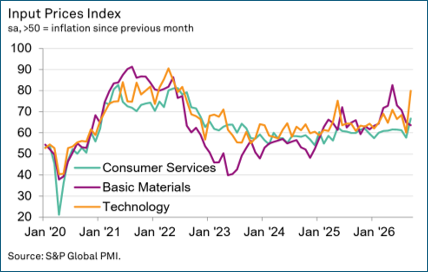 Source: S&P Global
ADP Weekly Pulse Report – Signals Continued Modest Growth in Private Sector Jobs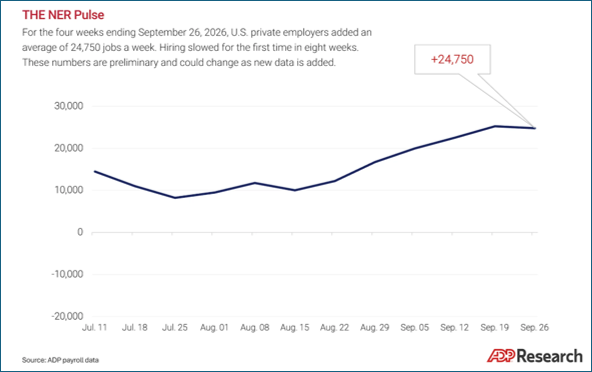 Source: ADP
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


