AI-Related Demand is Showing Up in More Places
- Yesterday was another good one for equities with the S&P 500 and Nasdaq 100 indices hitting all-time highs, no doubt spurred on by AI-related demand. Fixed income played along too as lower oil prices and increased shipments had some feeling better that the energy shock might be receding. However, this morning some of yesterday’s moves are being undone, and pricing pressure from AI demand seems to be showing up in more places. Below we discuss the latest trade deficit numbers with plenty of AI-related fingerprints on the wider-than-expected trade deficit and the latest ISM Services Prices Paid index hit a level last touched in 2023 in the aftermath of the post-Covid inflation surge. And while we noted that Treasuries participated in yesterday’s rally, new supply of 10yr and 30yr paper today and tomorrow may limit upside until the new debt is put away. Currently, the 10yr is yielding 5.34%, up 7bp on the day, while the 2yr is yielding 4.81% up 2bp on the day.
- The weekly ADP Pulse Report saw private employers add an average of 23,750 jobs for the week ending September 19 vs. 22,500 the prior week. This is the fifth straight week-over-week gain in the series and illustrates a less disappointing take on September employment than what the BLS delivered last Friday. It does, however, align with the low-hire, low-fire environment we’ve been in for most of the last year. The weekly total is a four-week average which provides some smoothing to week-to-week volatility. The latest weekly total rounds to a monthly figure near 100,000, above the recent run rate for monthly ADP job growth estimates. Does that imply a stronger October payrolls print?
- The August Trade Balance was also released yesterday, and the deficit was wider than expected at -$105.6 billion vs. an expected -$102.0 billion and wider than the prior month’s -$92.8 billion. This includes both goods and services and with the goods deficit reaching -$120 billion from a previously released report, it was the widest deficit since April last year when the Liberation Day announcement set off a flurry of rushed import orders to beat incoming tariffs. That goods deficit is being driven wider by AI-related imports of chips and other network/data gear and is another example of the numerous fingerprints the AI buildout is having on our economy.
- Year-to-date, the largest single import category is computers and the dollar value is more than twice that of the next category, passenger cars ($255b vs. $115b).The next three largest categories outside of cars and pharma, computer accessories ($159b), telecom equipment ($112b), and semiconductors ($90b) all have the smell of AI behind them as well and the YoY growth rates in those categories range from over 50% to near 100%. Keep in mind too that for GDP, imports are a subtraction so while the AI buildout is driving strong equity valuations for the companies involved, it’s not doing the same thing to US GDP.
- Yesterday also brought us the ISM Services PMI Index that revealed ongoing price pressure which is spilling over from AI-related fields into services. The headline number was 54.9 vs. 55.4 in August and 55.0 expected. The Prices Paid index, however, rose to 74.0 vs. 73.0 expected and 72.6 in August. It’s the highest for that inflation measure since 2023. New Orders (59.8 vs. 60.9 Aug.), and Employment (50.1 vs. 47.8 Aug.) rounded out the September results. Per ISM, the PMI level for September (54.9%) corresponds to a 2.1% increase in GDP on an annualized basis.
- This afternoon, the FOMC Minutes from the Sept. 19 meeting will be released. While the weaker-than-expected September jobs report may have been a fly in the ointment for those leaning on “labor market stability” we’ll see how heavily Fed officials relied on that in their discussions to hike. The disappointing jobs report has been followed by some soothing Fed speak so far this week and that has combined to whittle down odds for an October rate hike. Odds were over 70% last week before the jobs report and now sit around 22% this morning. If the Fed wants us to believe the October meeting is still “live” for a rate hike, the talk this week should leave that impression but so far that’s not the case.
- Finally, the Treasury began auctioning three coupon-bearing issues this week with $58 billion in 3yr notes yesterday. Auction results were decent, but that was the easiest of the three tranches. Today, the Treasury will sell $39 billion in 10yr notes, and $22 billion in 30yr bonds on Thursday. While the backup in yields to 20+ year highs should provide plenty of appeal we’ll see if more concession is still required. If so, that indicates price discovery is still pointing to higher yields.
ADP Weekly Pulse Report – Private Sector Job Growth Increases for Fifth Straight Week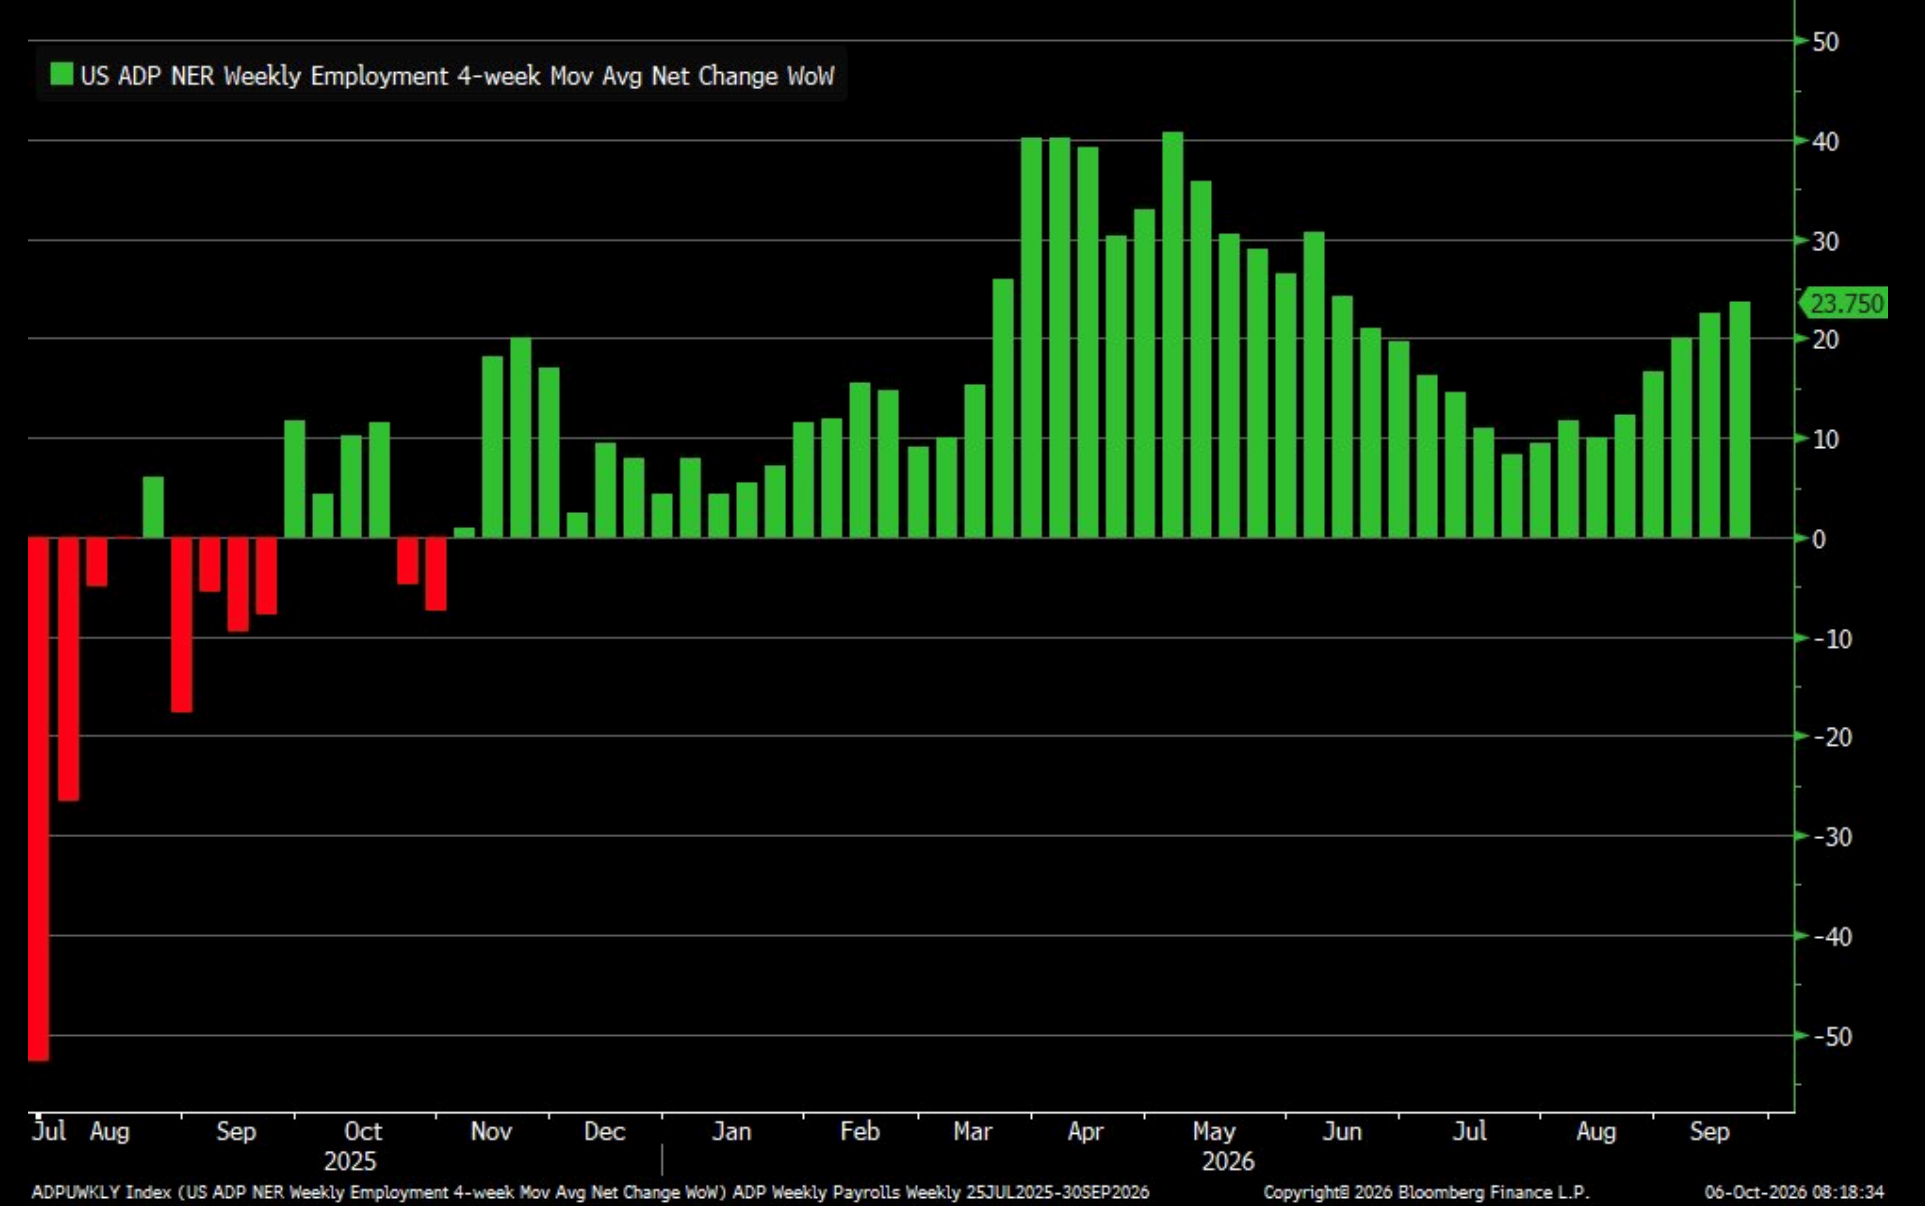 Source: ADP
Trade Deficit Gaps Wider on AI-Related Imports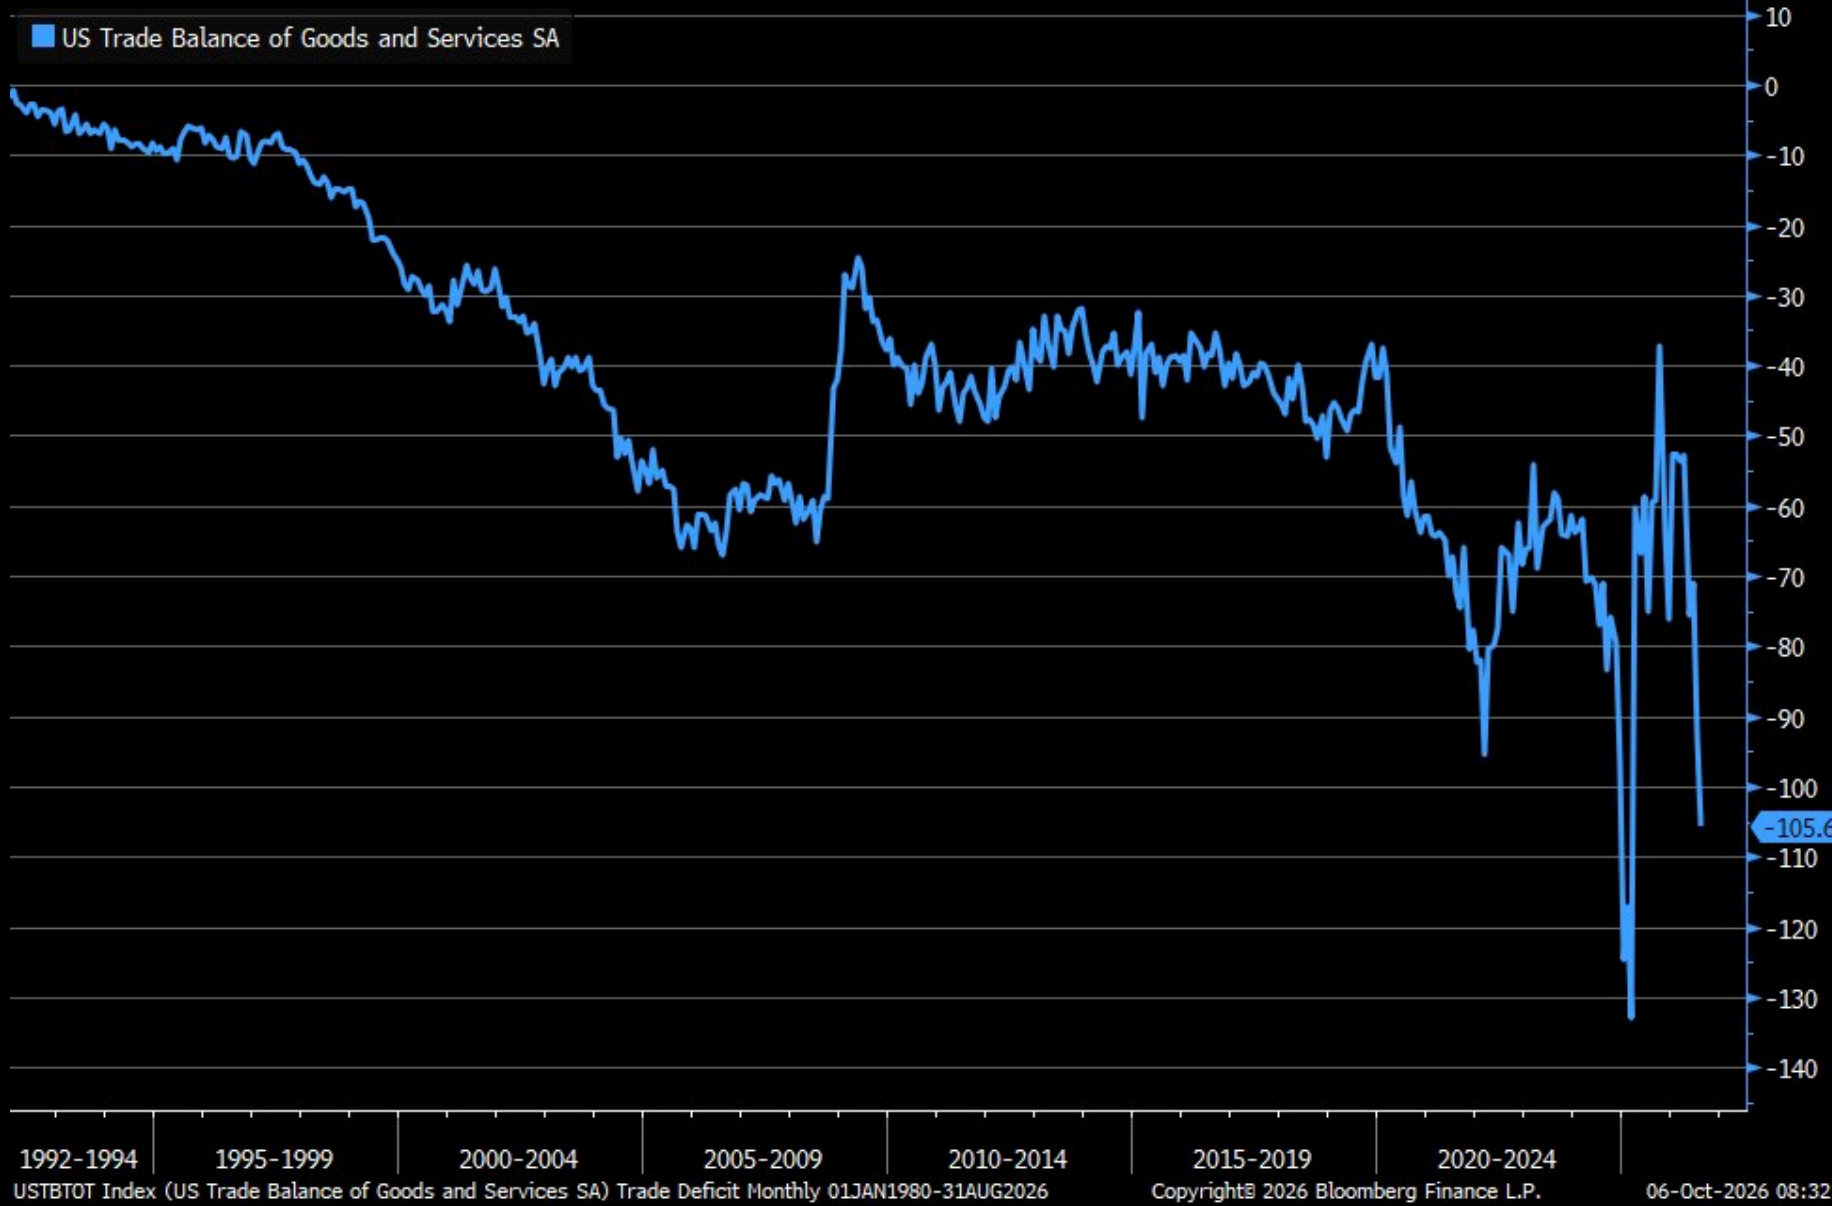
Source: US Census Bureau
ISM Services Prices Paid for September – Highest Since 2023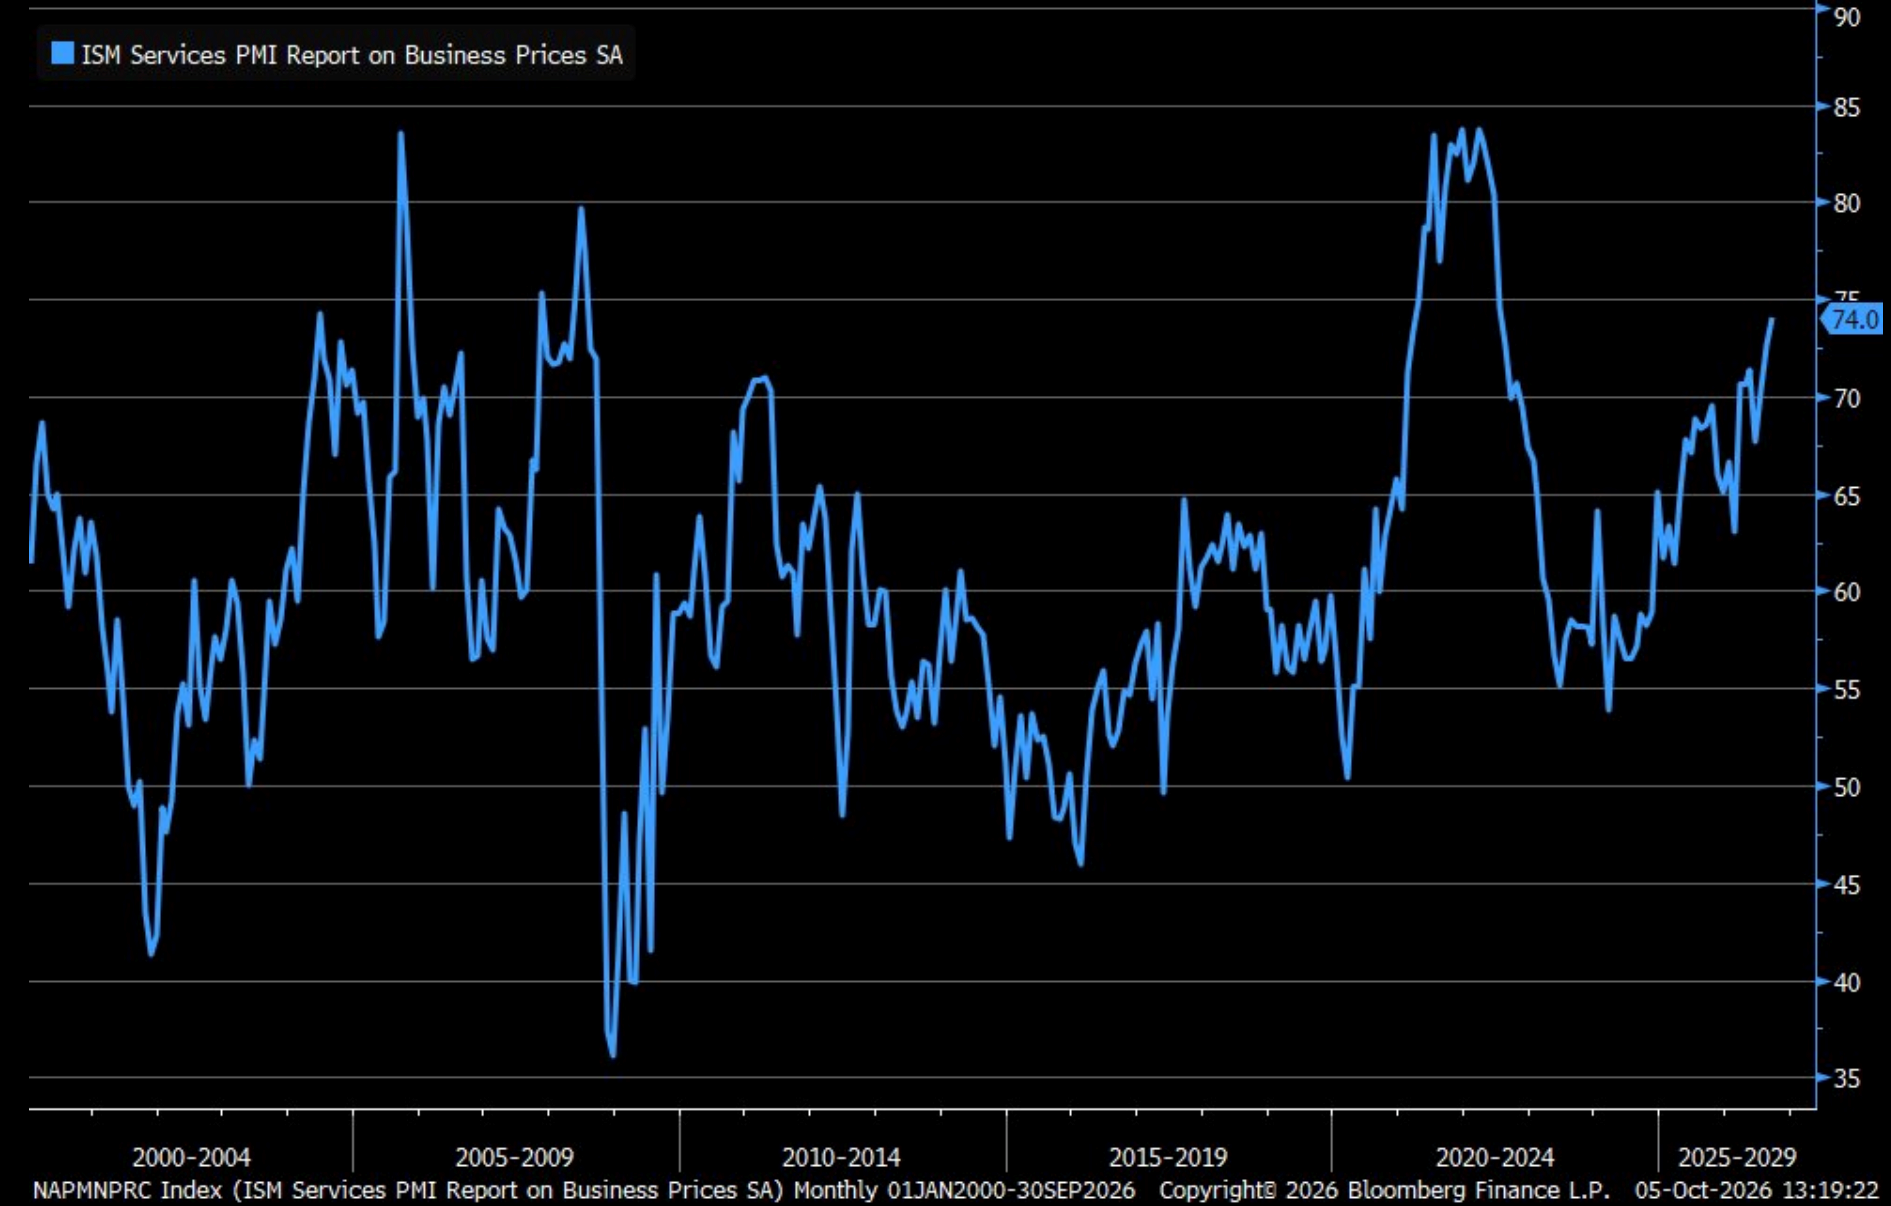
Source: ISM
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


