AI Stocks Continue to Struggle as Attention Shifts to the Fed
- AI-related stocks struggled again yesterday and that looks to continue with futures pointing lower this morning. This has helped boost Treasuries as a flight-to-safety trade supported a healthy bid in the safe haven security. Meanwhile, this week’s slate of thin data draws to a close with the preliminary S&P Global PMI series for October and the final University of Michigan Sentiment Survey due later this morning. Once those numbers are digested the market will turn its attention to next Wednesday’s FOMC meeting/rate decision where a hawkish pause is the overwhelming expectation. Stock market gyrations are rarely mentioned in Fed communications but if the risk-off trade continues it will have implications for the economy as consumer consumption could be dented from the equity drawdown along with a possible rethink in AI capex budgets. In summary, it looks like a full plate of concerns will be in place when the Fed meets next week. Currently, the 10yr is yielding 4.99%, up 4bp, while the 2yr is yielding 4.69%, up 5bp on the day.
- While this week has been light on economic data, perhaps the most important of the meager releases comes at the odd time of 9:45 am ET with the preliminary S&P Global PMI numbers for October. Recall last month the preliminary results were uniformly strong and that began a wave of Treasury selling with expectations of an October rate hike. The tone has changed in subsequent weeks, at least about the rate hike, as Fed speak uniformly talked down those expectations. In any event, the September Manufacturing PMI printed at 55.9, Services at 58.8, and Composite at 58.4. With 50 being the dividing line between a contracting and expanding sector the September results were strongly expansionary and the expectation for October is for continued expansionary readings but with slightly less strength than in September (see graph below). If you see a bump in yields today, it could be this report surprised to the upside once again.
- The other report due this morning, at 10am ET, is the final October University of Michigan Sentiment Survey. The preliminary results from early October had sentiment at new all-time lows and inflation expectations creeping higher. That’s not a good combination. What’s extraordinary about sentiment is that the preliminary reading was below the lows from 2025 (following the April tariff announcement) and mid-2022 (during the post-Covid inflation surge), and below the 2020 Covid period and 2007-09 Great Financial Crisis (see graph below). A further decrease in sentiment in the final reading would be quite the result given solid GDP numbers and low unemployment.
- Next week the action will accelerate with the FOMC rate decision on Wednesday being the highlight. While odds of a rate hike are low at 15%, the curiosity will be how much is communicated via the statement and press conference regarding expectations for December. While odds for a rate hike then are considerably higher at 90%, Fed Chair Warsh was non-committal in an address last week in Thailand. He prefers the less is more style of communication which has frustrated investors, economists, and analysts. It will be hard to remain non-committal after the latest inflation reports that were uniformly hotter-than-expected and could have easily led to an October rate hike. Keeping some inflation-fighting credibility will require more than being mute on the subject next week.
- The other releases of note will be the preliminary Durable Goods Orders for September due on Tuesday along with the Conference Board’s latest read on consumer confidence. The September Personal Income and Spending numbers with the PCE inflation series are due Thursday. Expectations for PCE are 0.5% MoM and 3.6% YoY and core PCE of 0.3% MoM and 3.1% YoY. The first estimate of third quarter GDP will also be released Thursday with expectations of 3.0% annualized growth and PCE inflation at 3.5% annualized and core PCE inflation of 2.4% annualized.
S&P Global PMIs Set New Highs in September Sending Yields Higher – Will October be a Repeat?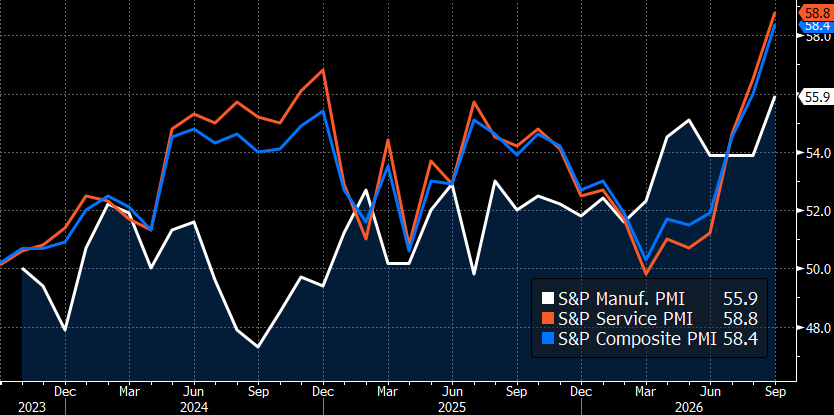 Source: S&P Global
Final Univ. of Michigan Sentiment for October Due at 10am ET – Will it Set Another New Low?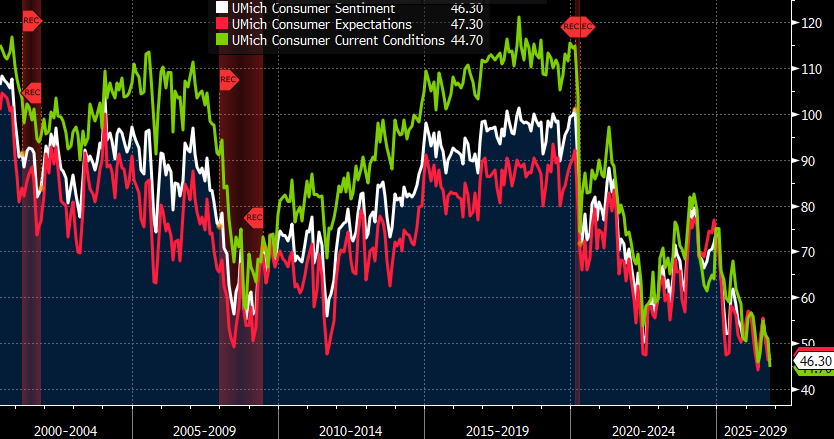 Source: Univ. of Michigan
University of Michigan Preliminary October Inflation Expectations – Creeping Higher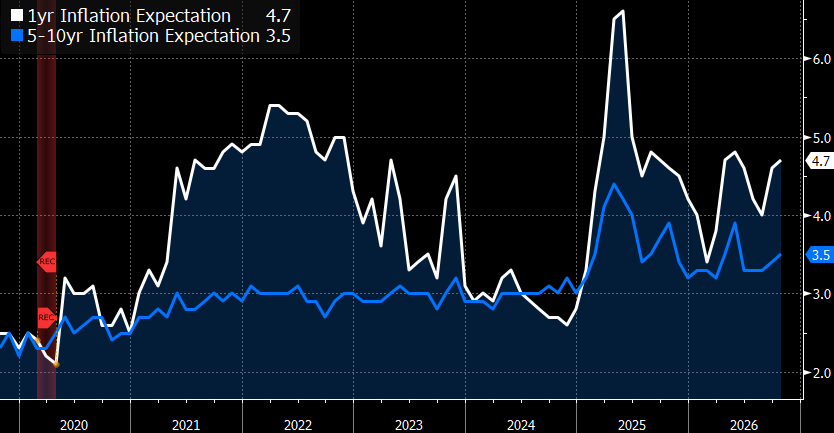 Source: Univ. of Michigan
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


