
August Core CPI Hotter than Expected, Odds to Hike > 80%
- August inflation data began arriving this week with the headline-leading CPI this morning. Results are discussed in more detail below but suffice it to say the monthly core rate was up 0.3% vs. 0.2% expected and odds of a September rate hike moved to 85% vs. 72% before the report. Thus, the stage is almost set for next week’s rate decision on Wednesday. I say almost because we never quite know what the weekend will bring regarding the Middle East situation and one last inflation report on Wednesday with August Import & Export Prices. That last report shouldn’t move odds materially on the hike/no hike meter, but it does hang out there, nonetheless. Currently, the 10yr is yielding 4.93%, down 2bp, while the 2yr is yielding 4.60%, up 5bp on the day.
- Today’s July CPI was near expectations on the overall but hotter on core and that has odds of a rate hike moving higher. Headline inflation was up 0.4% for the month, as expected. Recall, in July overall inflation increased a skinny 0.1%, with the YoY rate decreasing from 3.5% to 3.4%. The August YoY rate remained at 3.4%, which matched expectations. Energy costs were up 2.1% for the month vs. -1.5% in July and -5.7% in June as the brief Iran war ceasefire continued to fade away. The Food category was docile, increasing 0.1% for the second straight month. Thus, the spreading of higher energy costs that looked to be happening in March and April was harder to spot for a fourth straight.
- Core CPI increased 0.3% MoM (0.29% unrounded), a tenth hotter than the 0.2% expected, and July’s print. Despite the 3% increase in the core rate the YoY rate decreased from 2.5% to 2.4%, also matching expectations. That’s the lowest core YoY reading since March 2021. However, from here YoY improvement gets harder as a string of 0.2% monthly prints from 2025 roll off in the fourth quarter. Shelter costs rose 0.3% after two months at 0.1% which was the smallest Shelter print since January 2021. The increase here was driven primarily by lodging expense increasing 2.4% in August.
- A component of Shelter costs, Owners’ Equivalent Rent (OER), rose 0.2%, which is an improvement from the July 0.3% increase. In fact, in seven of the last eight months OER has ranged between 0.2% and 0.3% MoM. Pre-pandemic, OER – the largest single CPI component – also ranged between 0.2% and 0.3%. Getting OER to consistently print closer to 0.2%, or below, remains key for getting back to the 2% target. However, Core Services ex-Housing (aka Super Core) followed a modest July 0.2% increase (0.189% unrounded) at 0.5% (0.51% unrounded), the highest reading since January. The YoY rate increased from 2.84% to 3.00%. The uptick here will be hard for the Fed to explain away and adds weight to a hiking call next week.
- Yesterday brought us August PPI and combined with CPI will allow analysts to refine their PCE estimates numbers due at the end of the month. PPI met expectations, which were firmer than July and June given the higher energy prices during the month, and the line items that feed into PCE were generally firm which may inch up PCE estimates, and with median estimates in the 0.22% – 0.26% range keeps both a 0.2% or 0.3% PCE print a possibility. The final piece for PCE comes on Wednesday with the August Import/Export Price report.
- We continue to see the quest to reach 2% PCE inflation extremely challenging. The Middle East unrest seems to be expanding with the Iranian-backed Houthi militia group taking control of Mocha a key Yemeni city and port near the Bab el-Mandeb Strait which provides access to the Red Sea and entry way to the Suez Canal. That only adds to the supply pressure from the Strait of Hormuz blockage. Thus, elevated energy costs are likely to persist with no resolution on the horizon. Also, don’t forget the string of new tariff announcements which further increases pricing and supply pressure. Thus, with Warsh’s tough talk at Jackson Hole where he once again stressed the Fed’s primary goal is returning inflation to 2%, the market is looking for some follow-through which will likely require more than a single rate hike. If it doesn’t happen next Wednesday, expect a negative market reaction.
- Finally, the preliminary University of Michigan Sentiment Survey for September will be released at 10am ET. Recall in August, overall sentiment fell to 51.7 from 55.2 with expectations for a slight tick lower to 51.0. As the Fed wants inflation expectations “well anchored,” year-ahead inflation expectations will be a key reading with August’s at 4.2%, up from 4.0% in July. With the uptick in oil prices in August and early September, it’s not expected that much improvement will be found in the update as this series is more closely linked to the price of gas than some other consumer sentiment measures. For example, back in February, before the Iran war, the year ahead inflation expectation was 3.4%, and 2025 readings were in the 2.3% – 3.0% range. Long-run (5-10yrs) inflation expectations in August were 3.3%, the third straight month at that level. Can we make it four? In 2024, values ranged between 2.8% and 3.2%, while in 2019-2020, they were consistently below 2.8%. So, inflation expectations are not likely to build on July’s small improvement. They will remain above pre-war levels and pre-pandemic expectations. That will be noted by the FOMC Inflation Hawks.
Odds for a Hike Next Week Jump to 85% After August CPI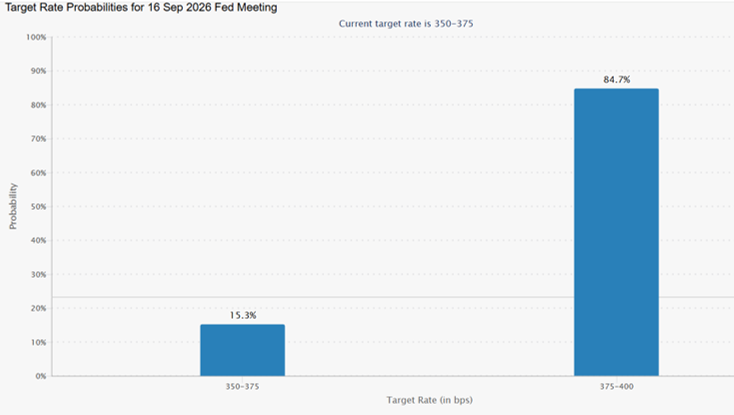 Source: CME Group
August Core CPI YoY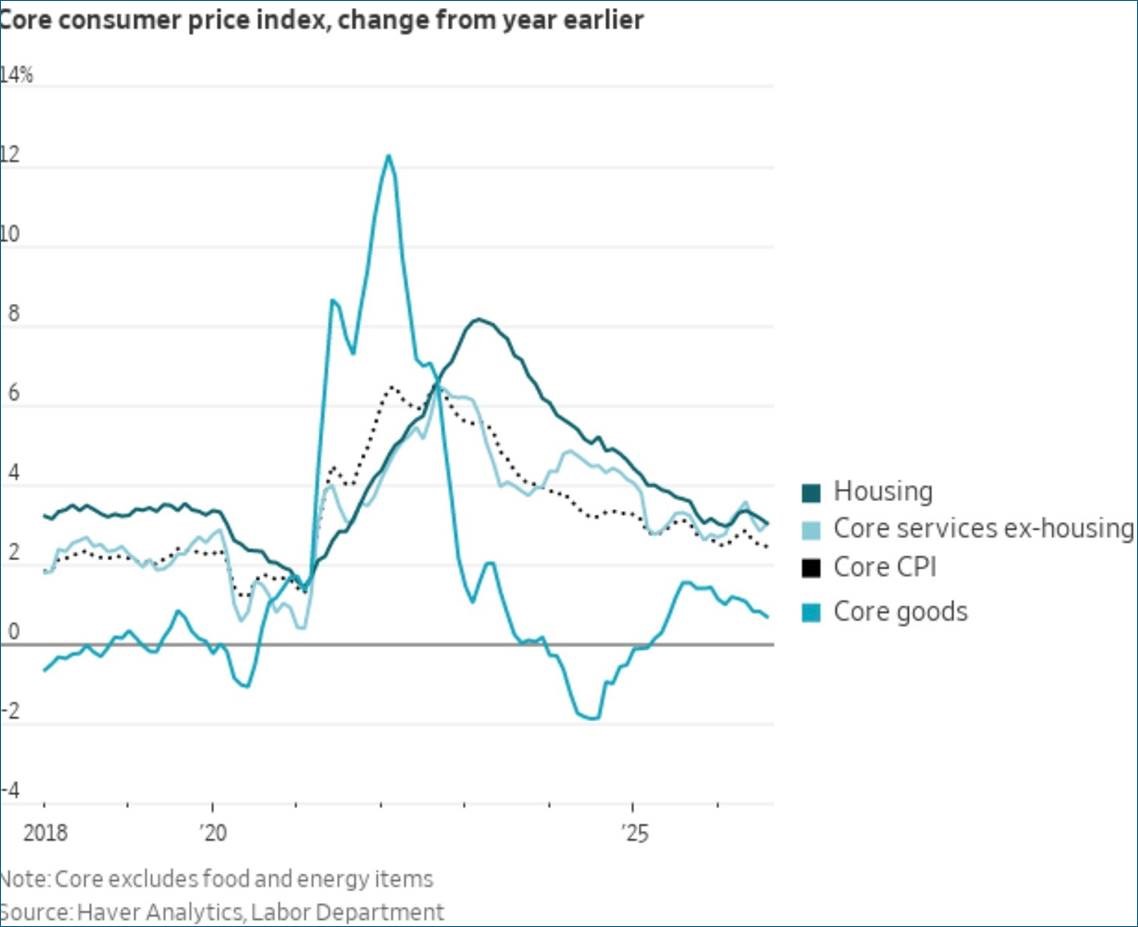 Source: BLS and Haver Analytics
Monthly Price Changes by Category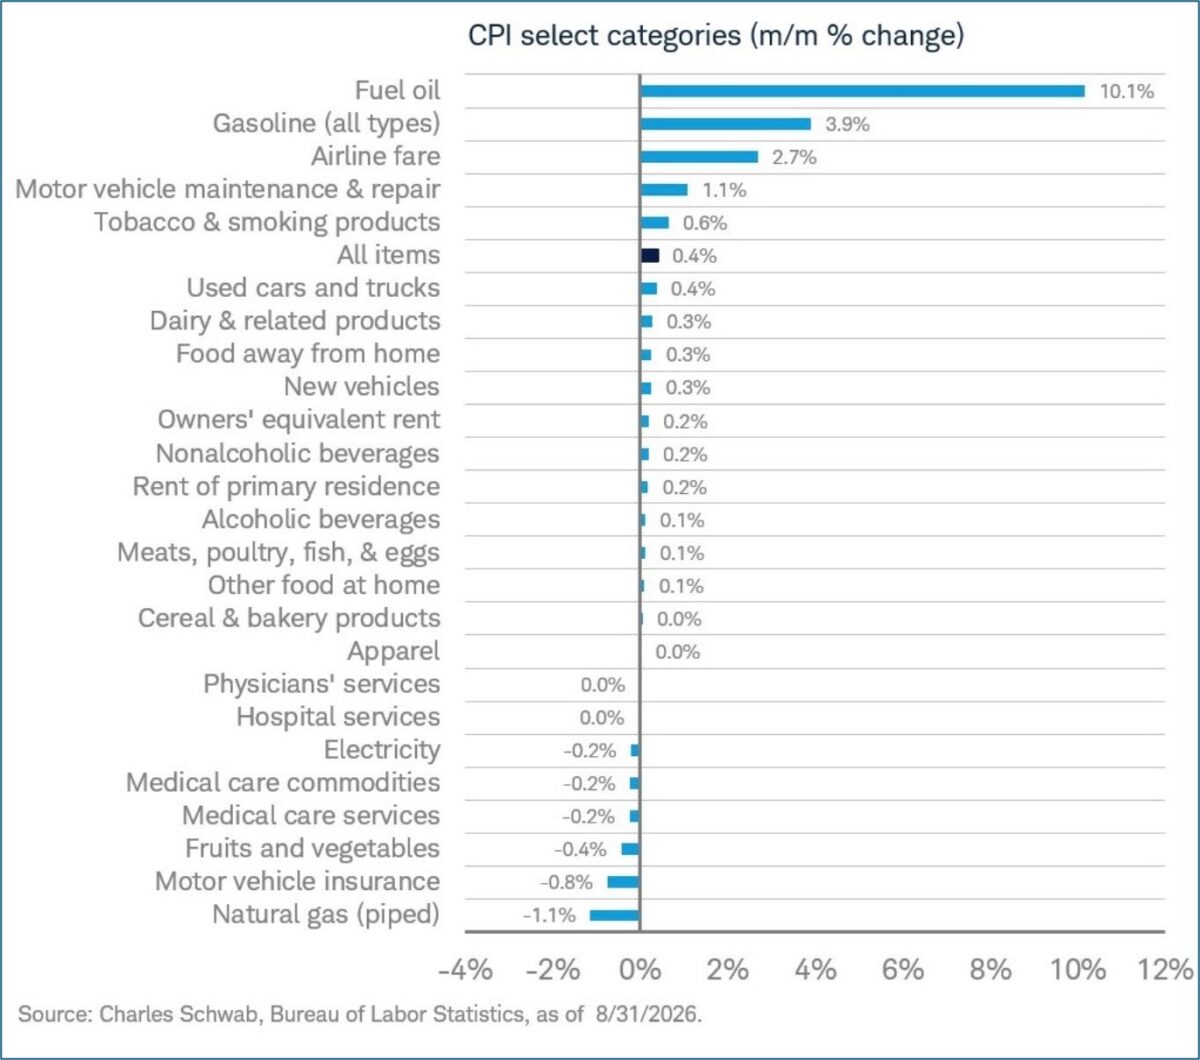 Source: BLS and Charles Schwab
Core Goods Continue Second Month of Increases While Core Services Moves Higher for Third Month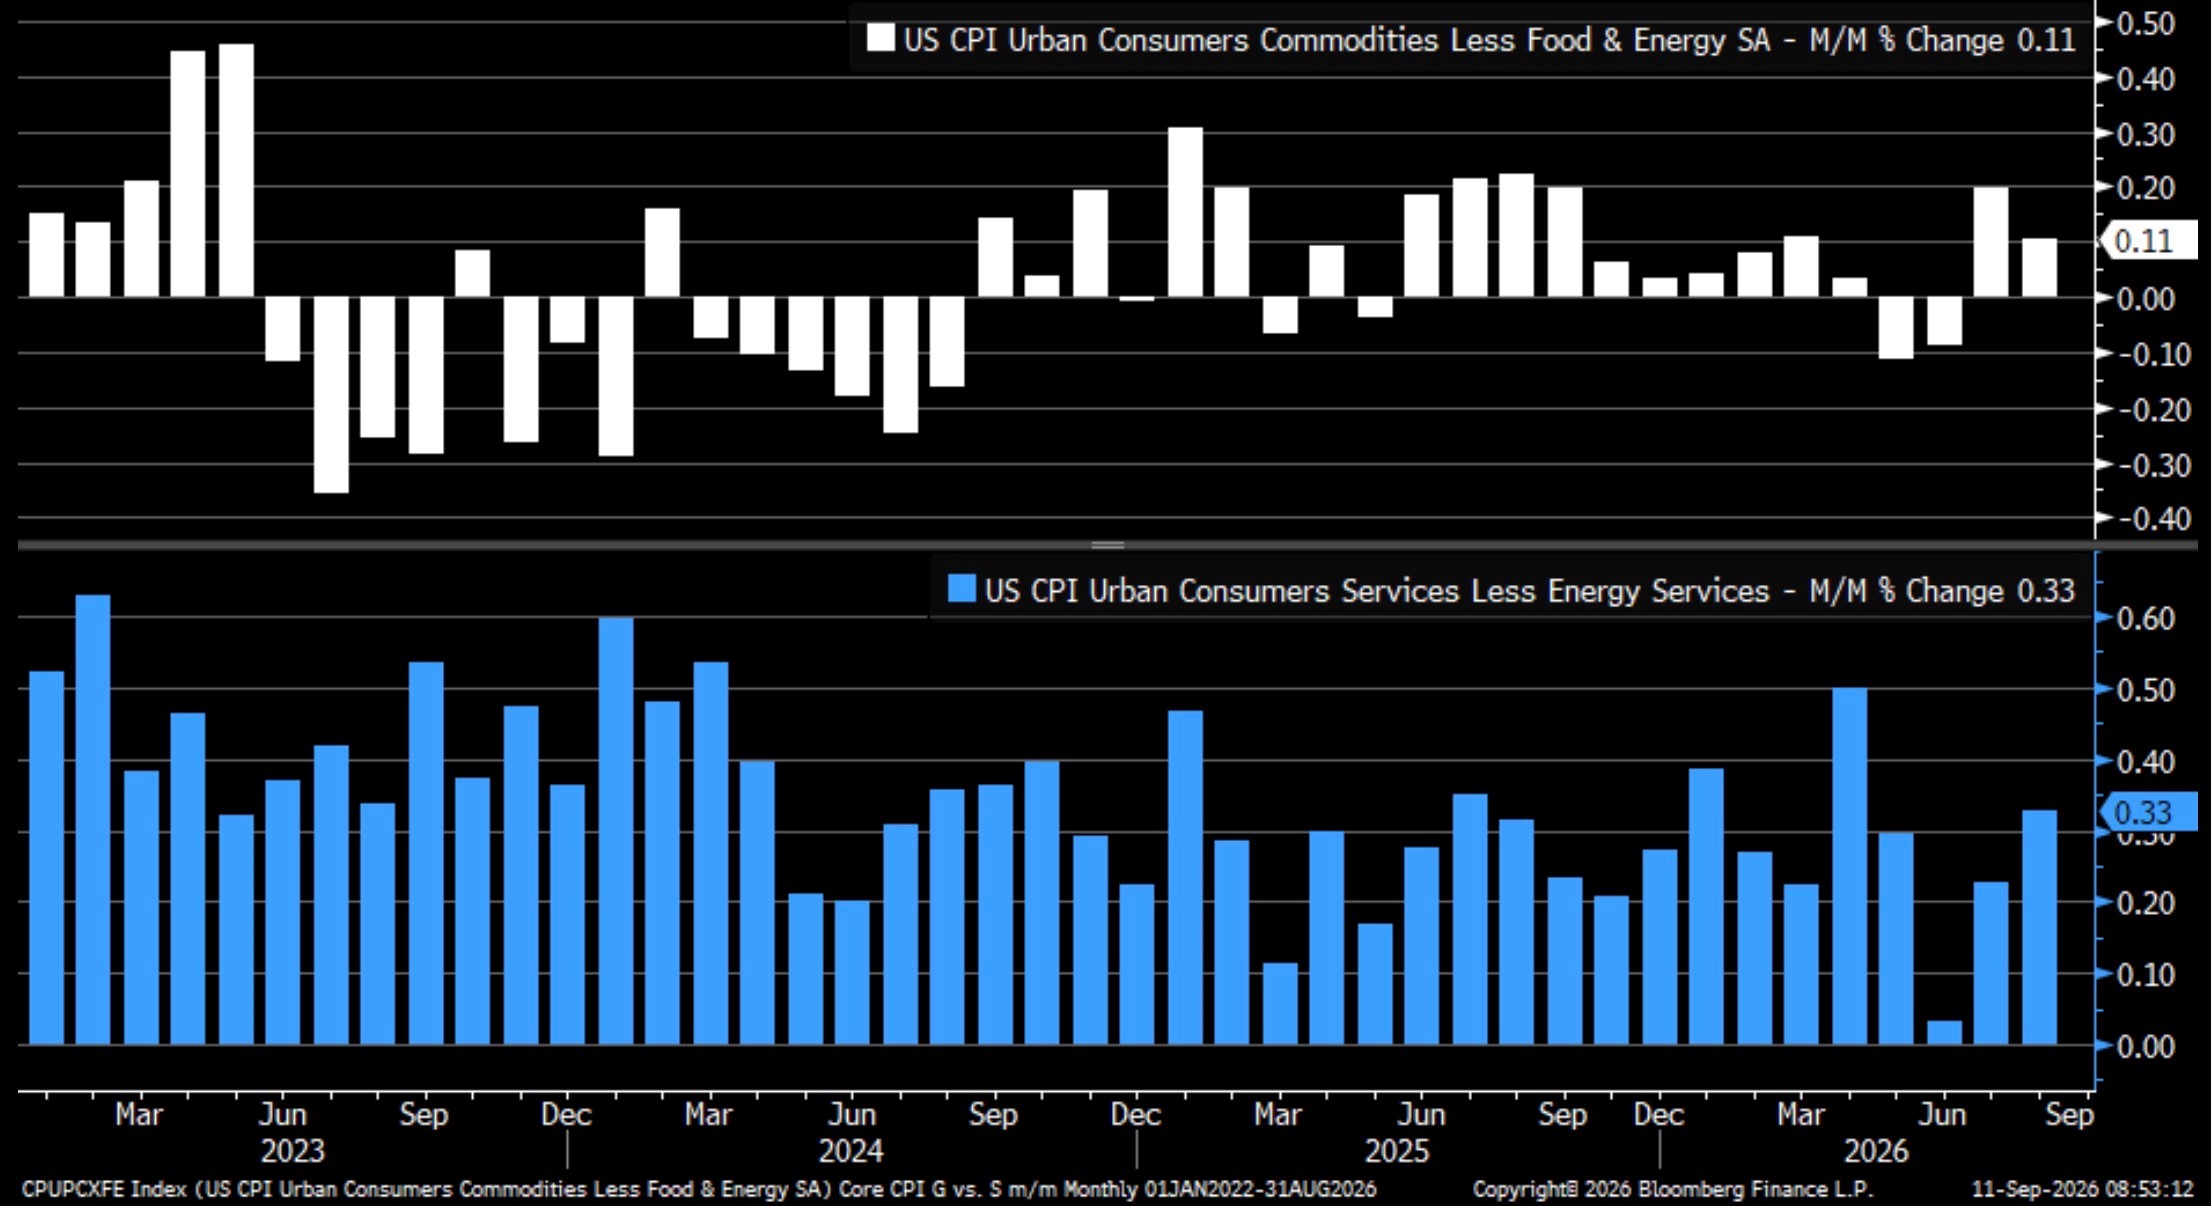
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


