August PCE Inflation Arrives
- A key release arrived this morning with the August Personal Income and Spending report, including the PCE inflation numbers. We discuss the report in more detail below. We also received a couple reports yesterday that saw another drop in consumer confidence, this time from the Conference Board, and a small dip in job openings for August via the Job Openings and Labor Turnover Survey. Fed speak has been on offer this week and yesterday NY Fed President John Williams influenced a short-end rally and long-end selling by noting that, “with the policy action we took at our September meeting, there is no need for urgency. We have time to gather more information. The accumulation of more data should provide greater clarity on the underlying trends in the economy and the associated risks to achieving our goals—and thereby the appropriate setting of monetary policy. If the economy evolves in a manner broadly consistent with my forecast, one further upward adjustment of the federal funds target range may be appropriate late this year to support a timelier return of inflation to target. But that is just my forecast, and time—and the totality of the data—will tell.” The implication to us is that the Fed has time to gather more data before considering further hikes, not that one more hike should do it. Nevertheless, the market took the comment and lowered odds for an October rate hike to 47%. So, we have plenty to ponder before getting to the Friday jobs report. Strap in! Currently, the 10yr is yielding 5.22% down 3bp, while the 2yr is yielding 4.83%, down 6bp on the day.
- The last of the July inflation numbers, and the Fed’s preferred measure, arrived this morning in the Personal Income and Spending report. Core PCE rose 0.2% (0.25% unrounded) vs. 0.3% expected and above the 0.13% July reading. YoY core PCE rose 3.0%, besting the 3.3% expectation. Overall PCE increased 0.3% matching expectations, and ahead of the 0.1% July result as gas and diesel prices remained stubbornly high. The YoY rate dipped to 3.4% vs. 3.7% expected. It reached 4.1% in April as gas prices hit their cycle high. With the monthly core PCE rate coming in under expectations and dropping to 3.0% YoY odds that the Fed will hike the funds rate another 25bp at its Oct. 28th were little changed at 47%. It should be noted the YoY rates underwent benchmark revisions with this release as price change methods for three categories were adjusted: portfolio mgmt. fees, computer software and services, and legal services.
- Another key figure in the report was personal spending for July that increased 0.9% vs. 0.8% expected and 0.2% in July. Spending adjusted for inflation was up 0.6% vs. 0.5% expected and above the 0.1% reading in July. The spending encompassed in this report is more comprehensive than the Retail Sales results reported earlier this month, but it does match the acceleration noted in that report. Thus, despite a dour mood, (see confidence report below), the consumer has rebounded off a so-so July with solid real spending in August. Thus, despite expressed frustrations over high gas prices, and prices in general, the consumer continues to spend, evidence that the K-shaped economy lives on for another month.
- Yesterday, the Conference Board’s latest read on consumer confidence for September was released with the headline confidence index dropping 6.7 points to 81.9, falling from August’s 88.6 and well short of the 89.0 expectation. It’s the lowest confidence reading in the post-Covid period. The dip was driven by a solid drop in both the Present Situation and Expectations index. The Present Situation reading decreased 7.9 points from 117.2 to 109.3, the lowest reading since 2021 while the Expectations Index fell 5.9 points from 68.2 to 62.3, the lowest reading since April 2025. Meanwhile, inflation expectations for the next year ticked higher from 5.8% to 6.1%, the second straight monthly uptick since March.
- Also, the Labor Market Differential (Jobs Plentiful – Jobs Hard to Get) softened as the share of consumers saying jobs are “plentiful” minus the share saying jobs are “hard to get” fell 2.5 points to 1.7% from 4.2% (downwardly revised from 7.5%). The slip this month and the downward revision to August dims some of the confidence in labor market stability after last month’s solid initial result and the subsequent beat on August payrolls. This result heightens the suspense over the Friday jobs report where expectations have been for another solid month of job growth and a stable unemployment rate.
- Also, yesterday the Job Openings and Labor Turnover Survey for August was released and openings slipped below expectations. The BLS reported that job openings declined to 7.079 million from a revised 7.335 million in July, coming in below market expectations of 7.23 million. The data illustrates a cool but still resilient low-hire, low-fire labor market. While down from expectations, openings sit at a 1-to-1 ratio with unemployed, but that’s down considerably from the nearly 2-to-1 ratio at the height of labor market demand coming out of the Covid lockdowns. The Quits Rate – a measure of worker confidence in finding better employment remained at 1.9% (voluntary quits divided by total employed). Similarly, the Layoff Rate remained at 1.0% (layoffs to total employed) indicating a stable labor market as of August.
- Finally, during our Elevate Banking Forum last week I had the opportunity to sit down with one of our guest speakers, Dr. Elliot Eisenberg, where we discussed why he gives the current economy a grade of B-. It’s an interesting, and we hope entertaining, conversation about where the economy is and where it’s likely to go. You can hear our 30-minute discussion here.
August Core PCE – 0.2% MoM, 3.0% YoY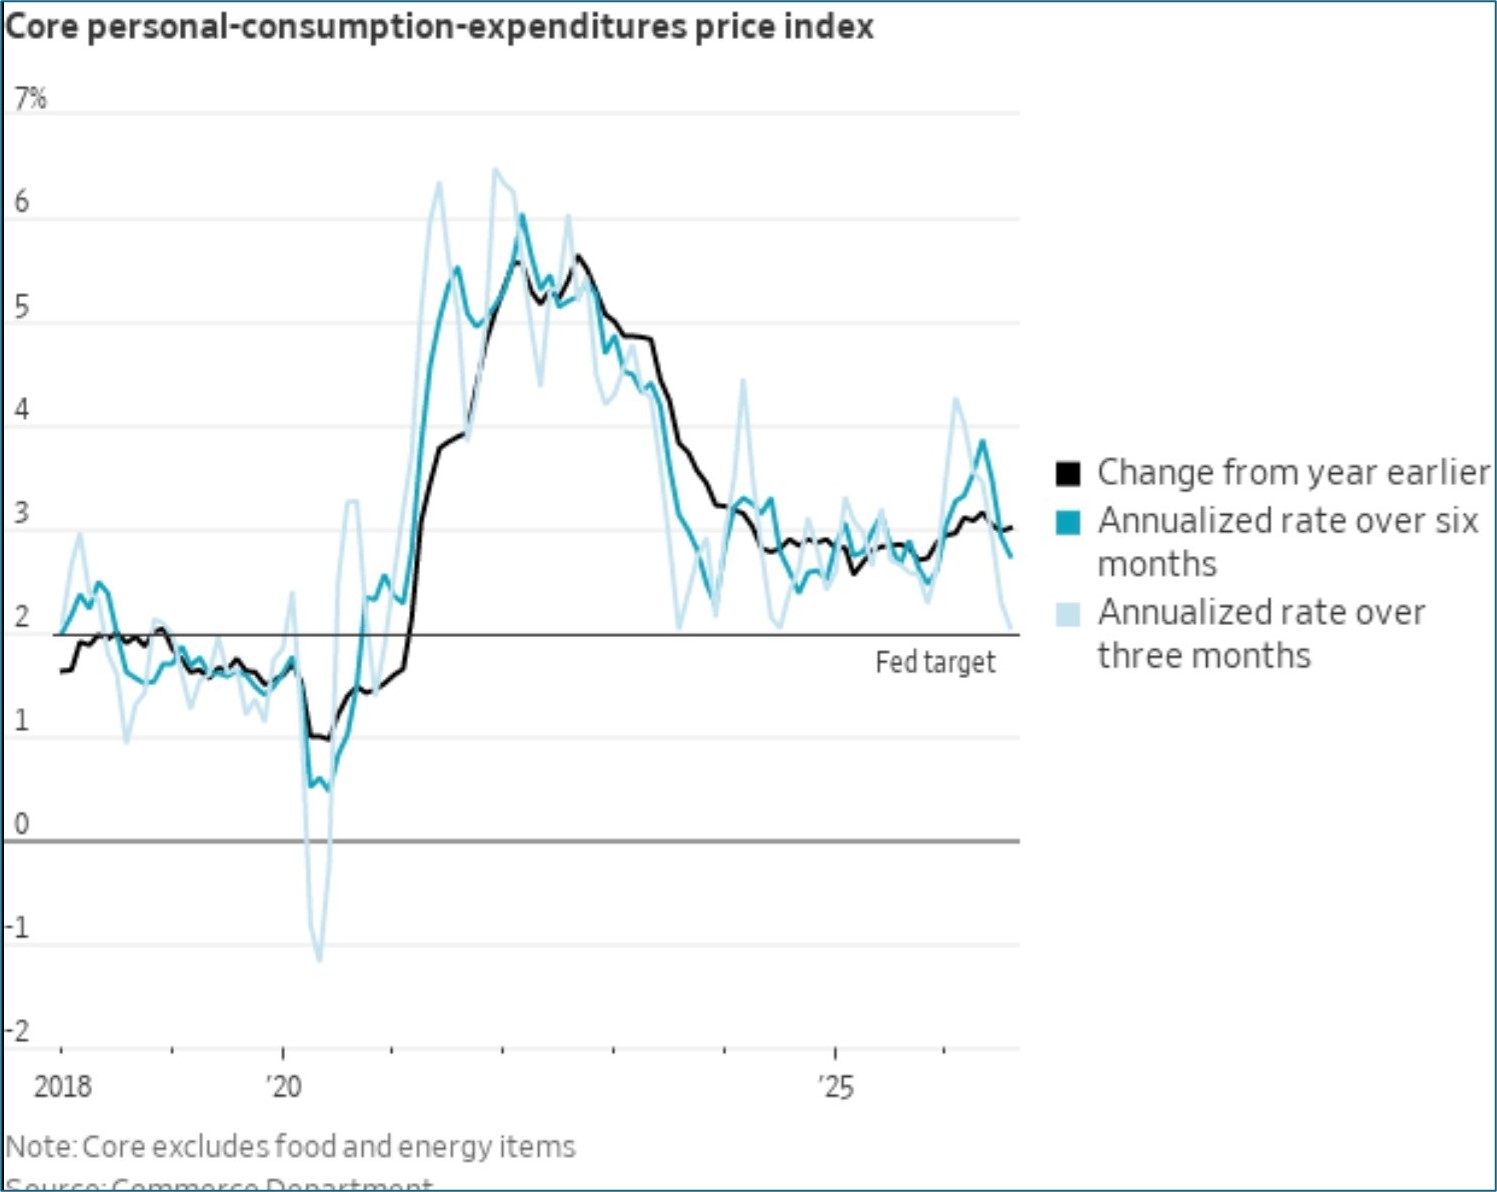
Source: BEA
August Spending by Categories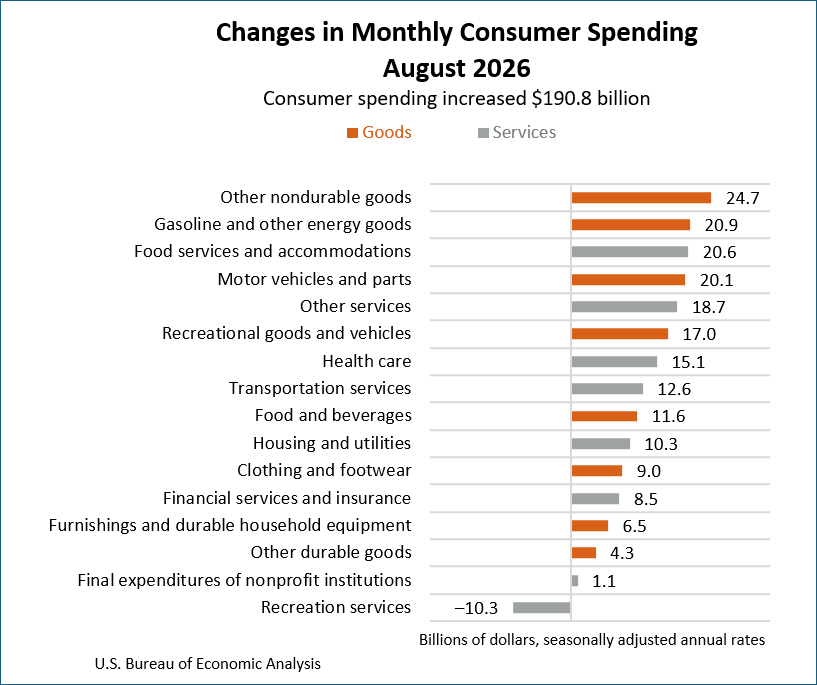 Source: BEA
Conference Board’s September Confidence Reading Drops to Lowest in Post-Covid Period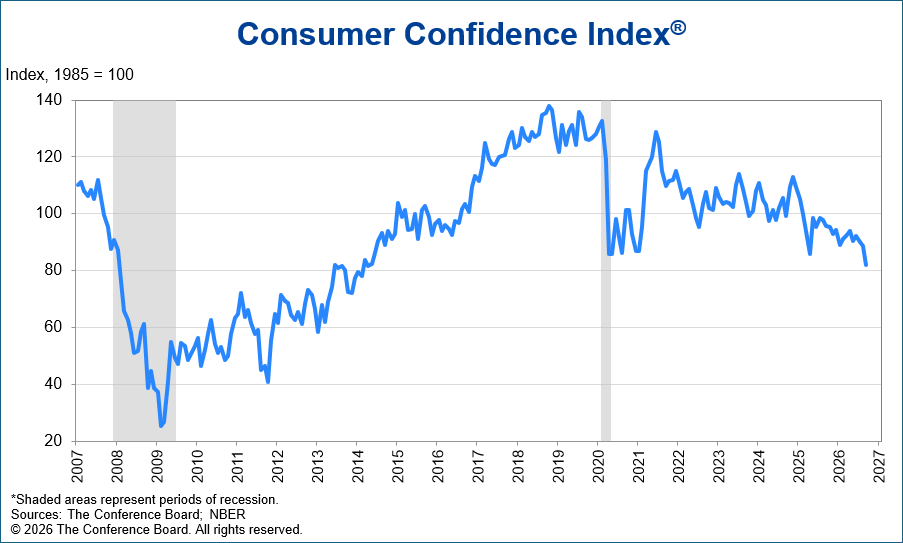 Source: Conference Board
Conference Board’s Present Situation and Expectations Index Drop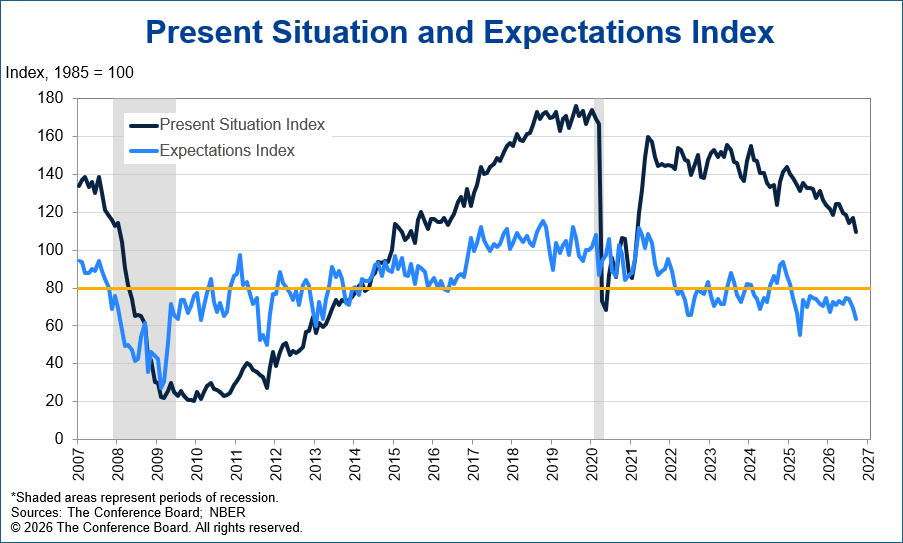 Source: Conference Board
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


