
Bond Portfolio Trends for Third Quarter 2026
Examining Bond Portfolio Trends: Third Quarter 2026
- Beginning in May 2012, we started tracking portfolio trends of our bond accounting customers here at SouthState Securities. At present, we account for over 130 client portfolios with a combined book value of $12.4 billion (not including SouthState Bank’s portfolio), or $95 million on average per portfolio. Twelve months earlier, the average portfolio size was virtually the same at $96 million.
Third Quarter 2026 Market Observations
- The third quarter of 2026 was characterized by a relentless move higher in yields across the maturity spectrum punctuated with the Fed hiking rates for the first time since 2023 late in the quarter. Inflation concerns remained front and center as a resolution to Middle East hostilities remained uncertain with elevated energy prices leaking into other non-energy sectors. In addition, the ongoing AI capital expenditures sparked their own price pressures but the consumer showed no signs of buckling under higher prices, waning wage growth, and shrinking savings rates. Add in fiscal concerns of $2 trillion annual deficits and total debt exceeding $40 trillion and the catalysts for higher yields took hold during the quarter.
- Short end yields moved higher as rate-hiking odds continued to increase as realized inflation data and increasingly hawkish Fed rhetoric made rate hikes a foregone conclusion. This pushed the 2yr yield from near 4.18% as the quarter began to a high of 4.89% as the third quarter ended. With effective Fed Funds at 3.86%, the 2yr yield is signaling another 100bp in rate hikes over the next two years.
- Meanwhile, the 10yr Treasury yield increased 82bp during the quarter ending September at 5.29%, reflecting the aforementioned inflation/growth/fiscal catalysts and a Fed firmly back in hiking mode. Higher yields during the third quarter were not only a domestic story but a global one as developed markets across the world experienced higher rates during the quarter. The era of extremely low rates coming out of the Great Financial Crisis and before Covid has reversed and the question now is how high will yields go?
Changes in Portfolio Allocations
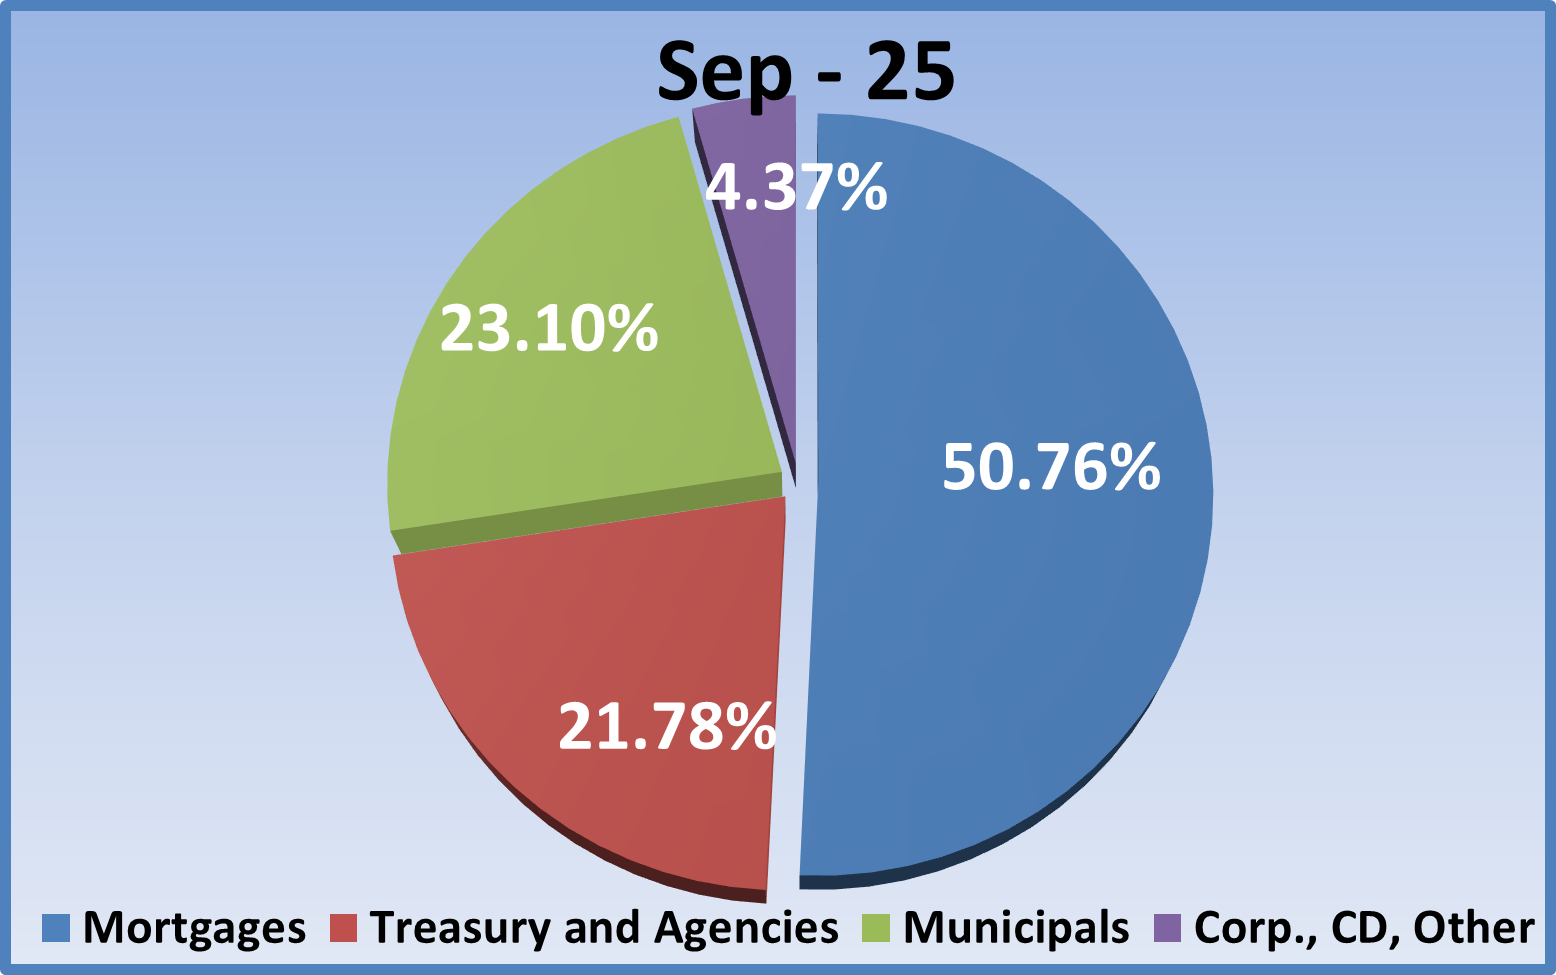
- Let’s begin our portfolio review by revisiting allocations a year ago as shown in the pie chart below. The MBS/CMO sector comprised 51% of the portfolio, Agency/Treasury investments were 22%, municipal allocations also stood at 23%, and the “Other” category (CDs, corporates, and other floaters) 4.4%.
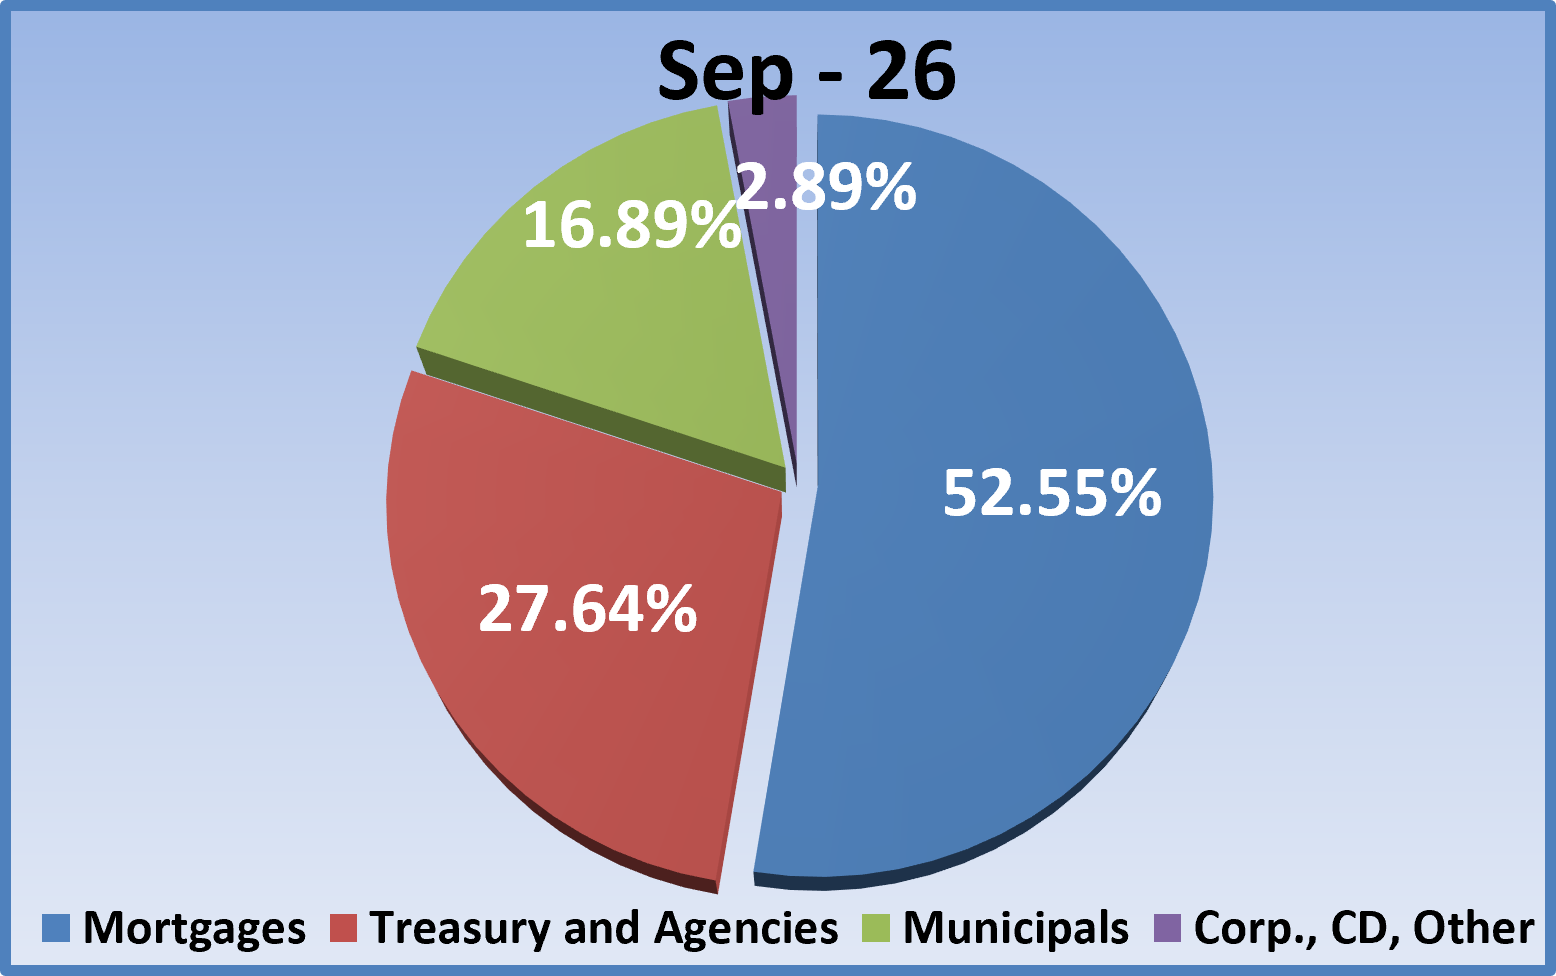
- Fast forward one year to September 30, 2026. The MBS/CMO sector increased to 53% of the portfolio, representing a 2% increase from last year. This repeats the experience of the past 18 months which halted a prior multi-year trend of declining MBS allocations. Before the Fed’s rate hiking cycle began in 2022, MBS tended to lead portfolio investments by a wide margin, typically 50% or more of total allocations. We are back to that allocation again.
- The Agency/Treasury sector has been the one area that experienced increased allocations during the hiking cycle, but it also remained strong during the Fed’s brief rate-cutting period that followed. Thus, allocations increased from 22% to 28% during the past year. The “Other” category was smaller at 2.9% versus 4.4% a year ago with corporate debt constituting more than 80% of the balance and CD’s the remainder.
- Municipal investments saw modest increases in allocation throughout 2024, but in 2025 additional investments slowed as investors shifted focus to MBS over municipal securities and this pattern has persisted through the first three quarters of 2026 with municipal allocations down to 17% vs. 23% a year ago.
Changes in Portfolio Performance
Now let’s look at portfolio performance trends. The graph below tracks average portfolio tax-equivalent book yield, duration, and unrealized gain/(loss) as a percent of book value. It also tracks 10-year Treasury yields and average portfolio size over the last two years.
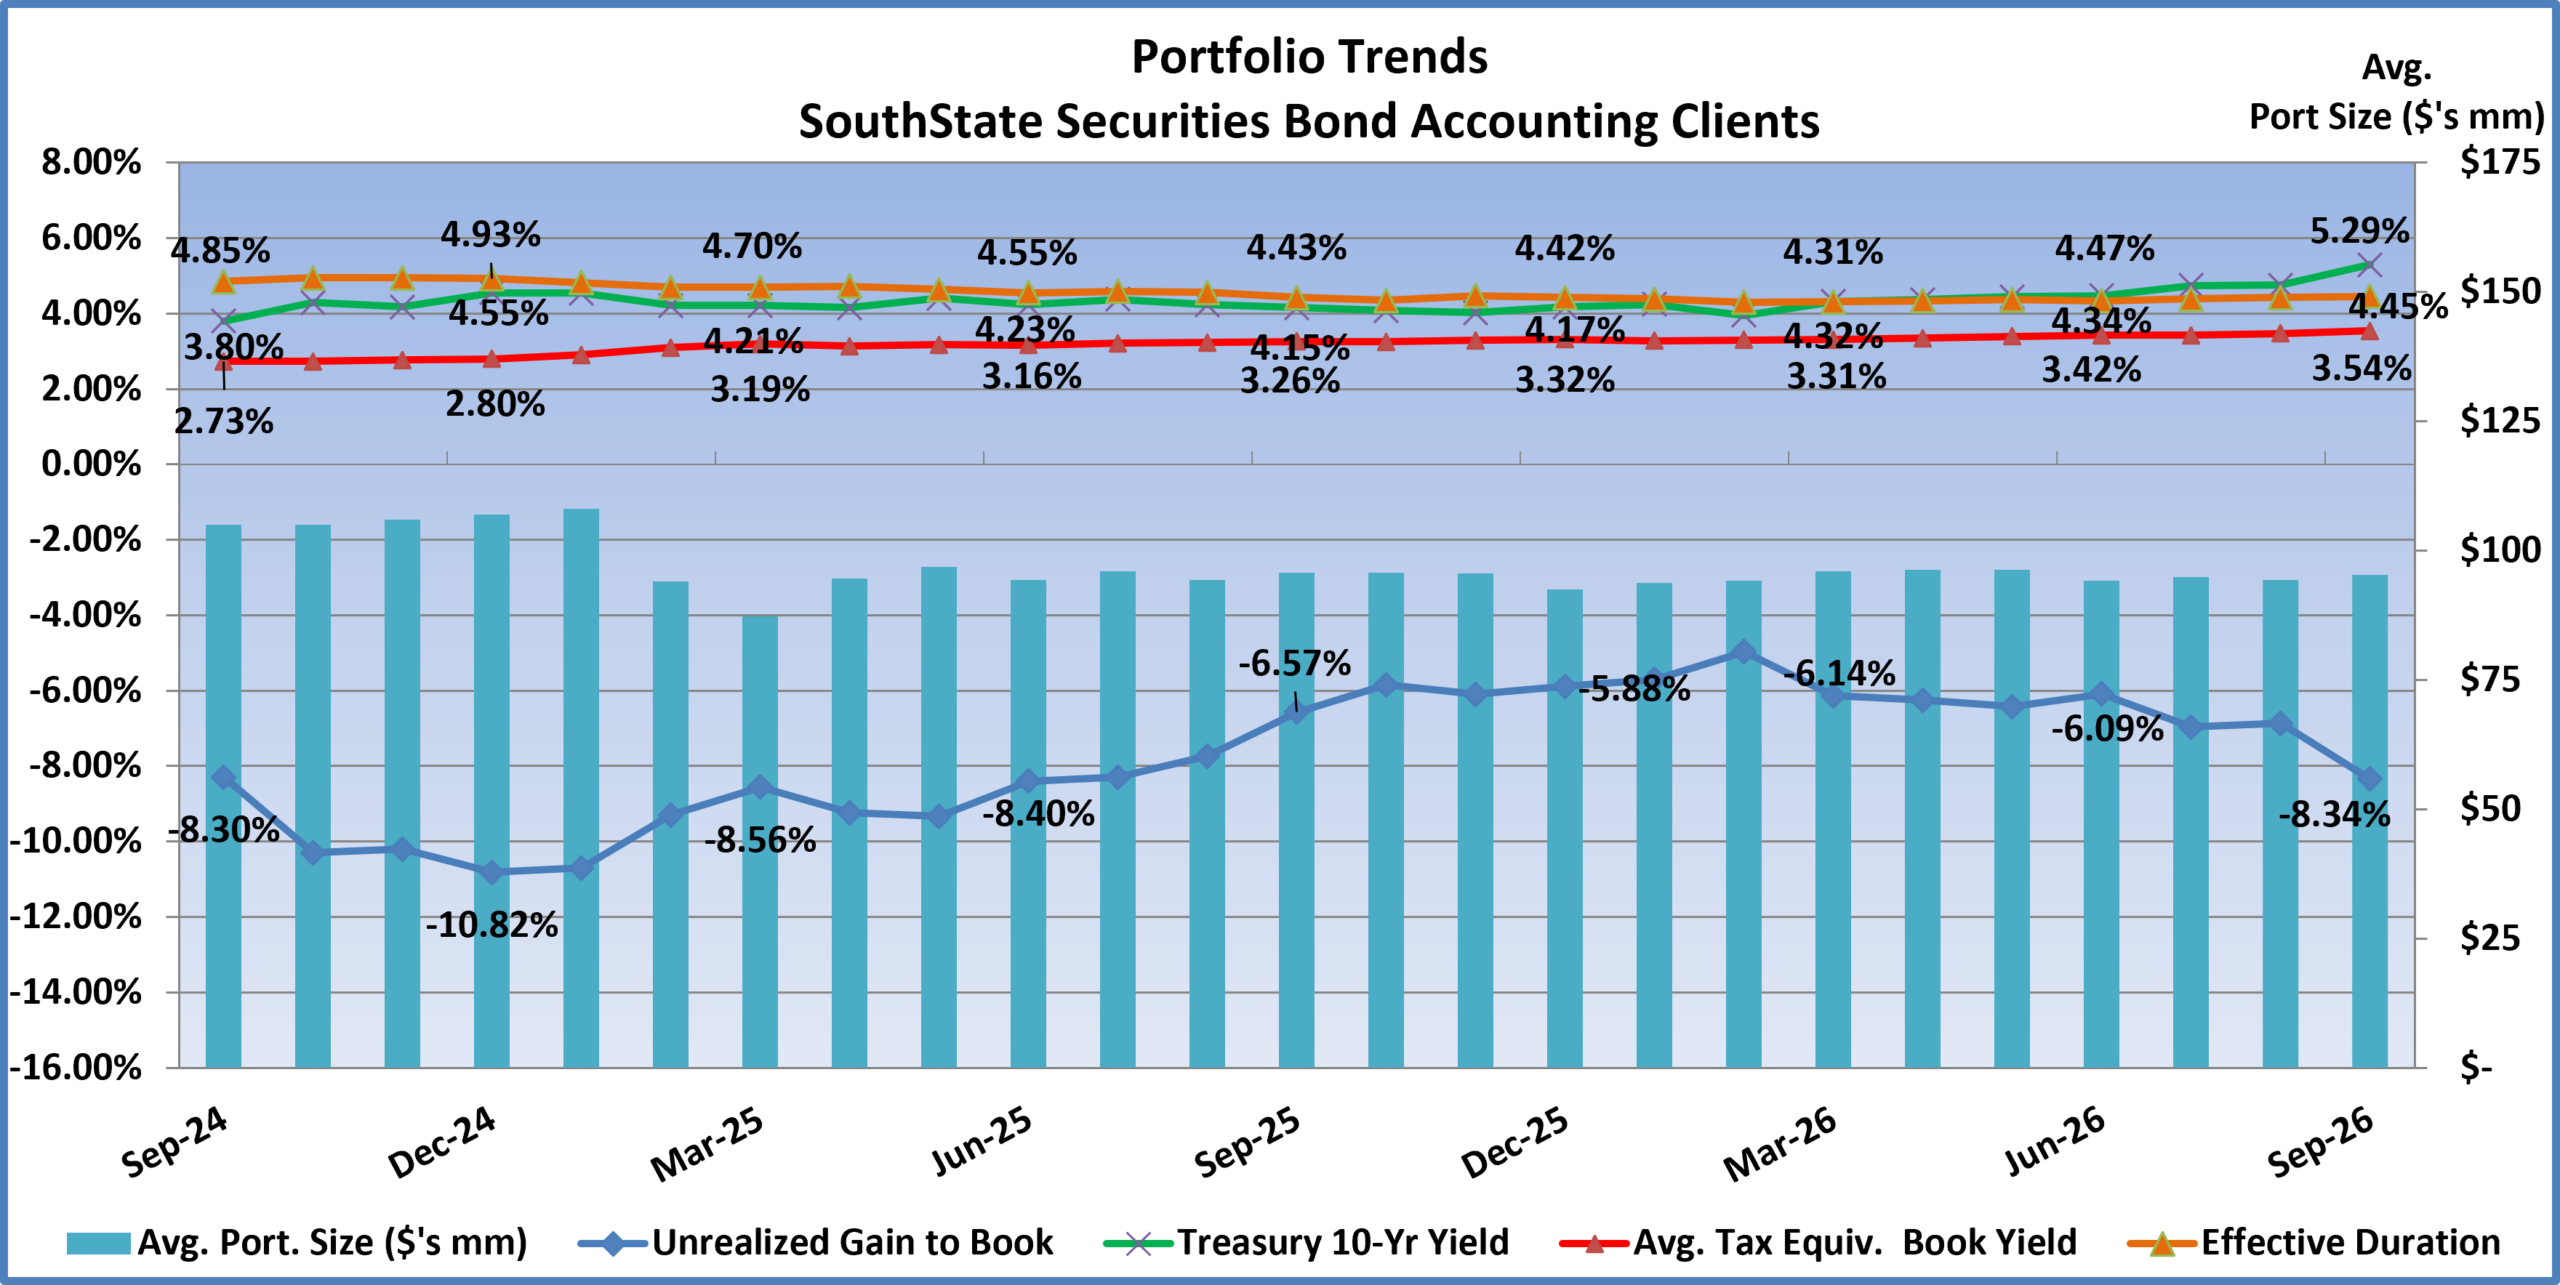
- Portfolio yields averaged 3.26% (red line) a year ago. As has been the pattern for a couple years now, yields have risen over the year as reinvestments were made at market yields exceeding lower legacy portfolio yields. By the end of September 2026, yields had increased 28bps from a year earlier to 3.54%. This increase in yield aligns with recent experience whereby quarterly yield improvement has averaged 7 to 8bp.
- 10-year Treasury yields (green line) a year ago were 4.15% and moved little in the next six months as investors waffled between worries over inflation and growth. Inflation worries intensified with the onset of hostilities with Iran and AI demand added to growth expectations helping to propel yields significantly higher, particularly in the last three months. The 10yr yield ended the third quarter at 5.29%, a whopping 114bp increase during the past 12 months.
- Average duration a year ago was 4.43 years and generally trended lower during the next six months as new investments were mostly shorter duration in nature. The average duration at the end of the third quarter was 4.45 years vs. 4.34 years as the quarter began. That slight duration backup is the result of higher market rates slowing call and prepayment expectations but it remains well short of the 5.50 year high when rate hikes began in March 2022.
- The portfolio’s unrealized loss started the quarter at -6.09% of book but slipped deeper into the red at –8.34% as the quarter ended. That reverses 15 months of improvement and is a consequence of the move higher in market yields that characterized the quarter.
Portfolio Purchases During the Third Quarter 2026
- New investments during the third quarter decreased slightly from the second quarter’s $1.3 billion to $1.2 billion, or $8.9 million per portfolio on average. By way of comparison, in the year ago quarter, purchases totaled $1.3 billion. So, quarterly purchases have generally been flat from year ago levels but decreased slightly on a sequential basis. The good news is the run rate of purchases prior to the pandemic was approximately $1.2 billion per quarter, so this is the fifth straight quarter where purchases exceeded pre-pandemic levels despite the slight sequential decline.
- The Treasury/agency sector continued to be the top sector with a strong 58% of total purchases (56% Treasury, 2% agency). The MBS/CMO/SBA sector followed with 35% of the total. The municipal sector was once again lapped by the top two categories with just 2.4% of purchases, (1.9% tax-free, 0.5% taxable).
- Average tax-equivalent book yield for third quarter purchases was 4.39% vs. 4.12% in the prior quarter. The average effective duration of purchases was 2.23 years versus 2.26 years in the prior quarter. So, investors earned 27bp more yield with effectively the same duration in purchases which speaks to the increase in market yields during the quarter.
- Compare the quarterly purchase metrics to the legacy portfolio book yield of 3.54% and effective duration of 4.45 years.
- We’ll be back in January with a review of fourth quarter performance and purchase analysis.
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


