
Decision Day for the Fed
- We’ve reached the point in the week where the Fed takes center stage. The market has convinced itself that a 25 bp hike is coming which would push the Fed Funds range from 3.50% – 3.75% to 3.75% to 4.00%. Of course, the Fed could always surprise us by holding pat but if that does happen expect more selling in the long-end as questions about the Fed’s inflation-fighting credibility and independence from a White House that has been clear about wanting rate cuts will echo long after the meeting is over. However, it’s not all about the Fed today, as we received the latest on the health of the consumer with August Advance Retail Sales, and a final piece of the inflation puzzle for PCE with August Import/Export Prices. We review the results of those reports below. Currently, the 10yr is yielding 4.98%, down 2bp, while the 2yr is yielding 4.63%, down 3bp on the day.
- It’s Fed Decision Day and the prohibitive consensus view is that the FOMC will vote to hike rates 25bps. The decision will be announced at 2pm ET, followed by a Warsh press conference. We agree with the consensus view and will add that it will also be a hawkish hike. What we mean by that is that the messaging and press conference will make clear this is the first of probably more hikes to come. So, how many more? The futures market has two hikes fully priced in by year-end with 28% odds of a third hike. The odds for that third hike, however, get larger by the March 2027 FOMC meeting and a fourth becomes a real possibility when looking at the June 2027 FOMC meeting odds.
- Almost as important as the rate decision will be the refresh of the SEP (Summary of Economic Projections) along with the Dot Plot of expected Fed Fund rates over the next several years. In fact, the Dot Plot will be analyzed as it now approximates the only forward guidance one will get from a Warsh Fed. Recall, the June FOMC data refresh had the year-end 2026 median dot reflecting one hike. Six of the eighteen dots were 4.125% or higher, implying two hikes, so it would take three in the June one-hike camp to increase their projections to bump the median to a two-hike forecast. Three of those dots were at 3.875% so those are the most likely to add another 25bp to their 2026 year-end projection which would move the median to two hikes. Three hikes by year-end would take a big shift from June, and given the limited inflation moves in the interim, we suspect a two-hike forecast with today’s updated Dot Plot.
- The 2027 dot will be informative as well. Recall, the June Dot Plot had the median at 3.625%, calling for a single rate cut in 2027. In fact, the dots in general shifted lower in 2027 as FOMC members saw inflation slowly easing in 2027. Will that still be the case? One can speculate a resolution to the Middle East situation will bring some energy price relief, but the speed of that happening is still highly uncertain and thus we see it likely that the 2027 median dot shifts to one or two rate hikes. That would put the total move at 100bp in hikes with a downward trend in 2028 and Longer-Term. The decreasing trend, however, in those two out years are likely to be less than the June version which had the Longer-Term dot, or the neutral rate estimate, at 3.06%. That’s probably due for an uptick to 3.25%, or slightly higher. What is clear is we’re likely to see a reflection of the current market’s upward trend in yields reflected in today’s Dot Plot.
- With rate hikes likely, the question shifts to will they be effective in bringing down inflation? Part of the upward move in long rates has been the lack of Fed action. Thus, with the increased odds of a hike, 10yr yields were nearly unchanged on Friday after the solid nonfarm payrolls number. A hike today, followed by a messaging of more to come will likely induce a long-end rally as the market realizes the Fed is not all talk. The AI buildout, however, will continue and the price pressure and demand that places on the economy will not be impacted by a 25bp rate hike. Thus, with that source of price pressure still in place, and as long as the energy shock continues, inflation numbers are not likely to show dramatic improvement. The messaging on the Fed’s inflation fighting intent, however, will be a new input into the bond market calculus that has been missing to date.
- This morning, the August Advance Retail Sales beat robust expectations after a disappointing July. Headline sales increased 1.2% MoM, easily beating the 0.8% expectation and well ahead of the disappointing -0.5% July decrease. Sales ex autos and gas were up 1.2% vs. 0.4 expected and better than the -0.3% dip in July. The core spending category, the so-called Control Group, posted a 1.4% increase vs. 0.5% expected and well clear of the -0.4% in July. The control group gain was the largest since September 2024. In summary, it was a nice rebound after a disappointing dip in July that looks now more like the consumer pausing to a catch their collective breath rather than a more durable downturn in spending. Also, internet sales rebounded from a dip of -1.7% gaining 2.6% in August. There were timing issues around internet sales and Amazon’s Prime Day which occurred in June, earlier than prior years, which threw off the seasonal adjustment for July. In summary, it provides another signal to the Fed to pursue the price stability mandate as the consumer appears healthy once again.
- The penultimate August inflation report was delivered this morning with the Import/Export Price report. The Import Price Index increased 0.7% vs. 0.5% forecasted and July’s upwardly revised -0.3% result (originally reported as -0.4%). The YoY rate increased from 5.9% to 7.7%. Ex-petroleum, import prices rose 0.8% vs. 0.3% expected and higher than the 0.3% gain in July. Monthly price gains by country were as follows: China (+1.0%, largest monthly gain since 2004 with YoY at 3.0%; driven mostly by computer-related products), Japan (+0.2%, 1.1% YoY), Mexico (+0.1%), Canada (-0.8%, the second straight month of declines which were the first since 9/25). With this report, analysts have all the pieces to finish PCE estimates which will be released Wednesday, September 30. Currently, estimates are tracking closer to 0.3% for core PCE and while coming well after today’s FOMC meeting will buttress today’s expected rate hike.
Odds for Three Hikes by Year-End Inching Higher at 28%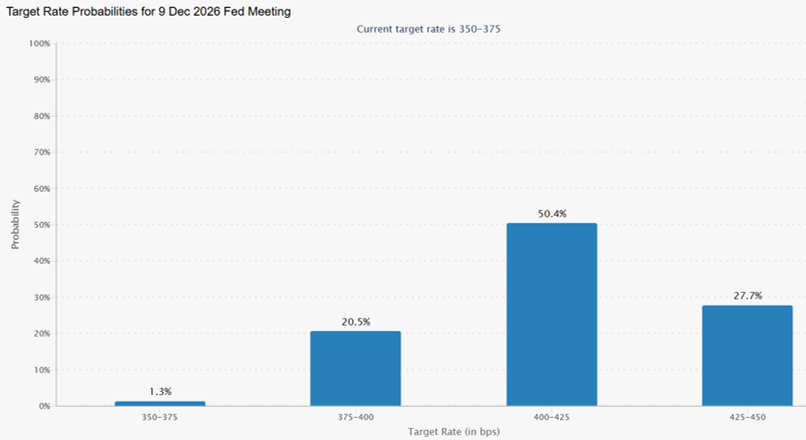 Source: CME Group
June Dot Plot – Likely to See an Upward Shift in Today’s Edition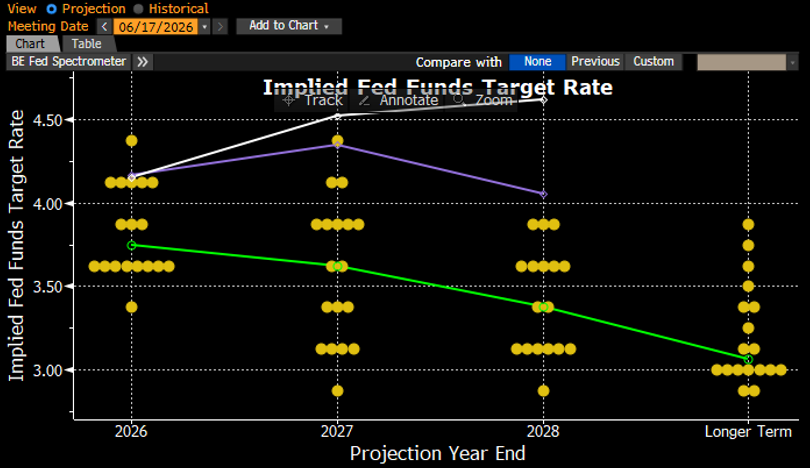 Source: FOMC
Think an October Hike is Unlikely Before Upcoming Election? Think Again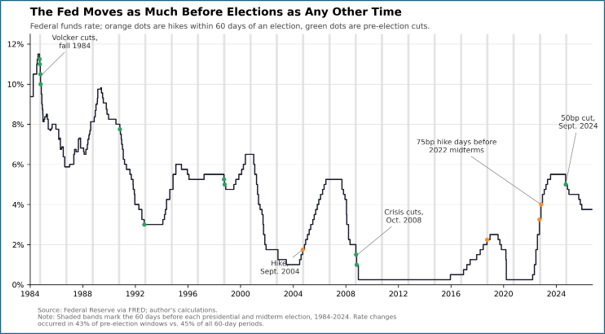 Source: Federal Reserve and Claudia Sahm
August Retail Sales Control Group (Core Sales) – Largest Increase Since Sept. 2024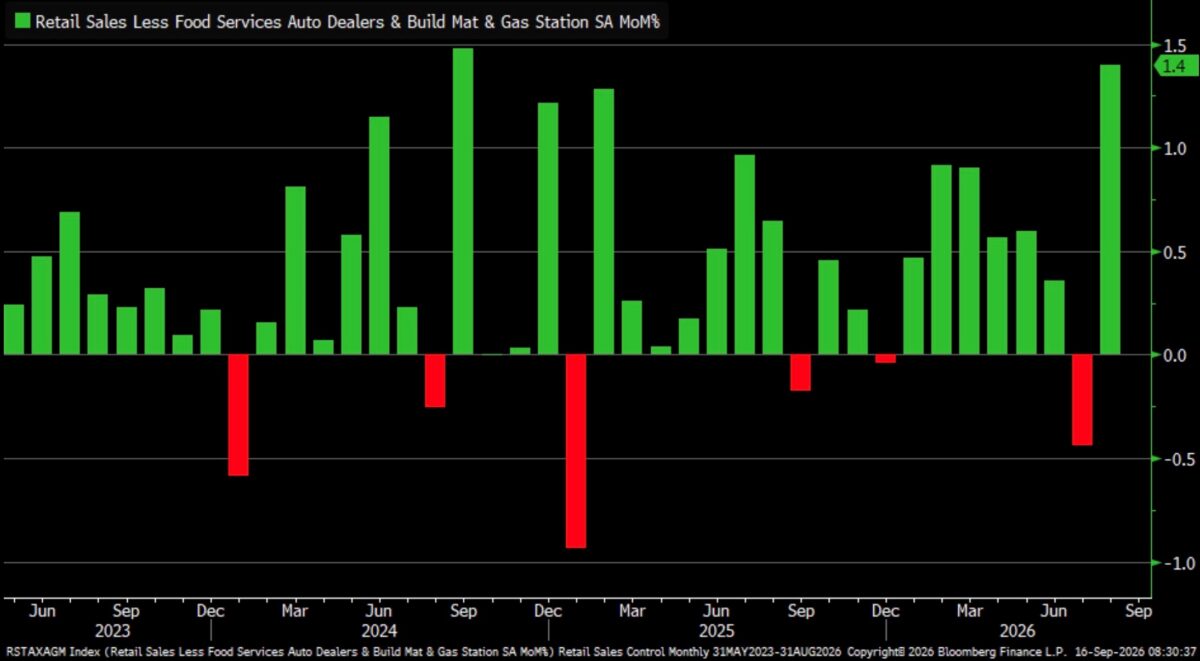
Source: US Census Bureau
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


