
Expect Plenty of Fed Speak this Week
- After last week’s obstacle course of a highly anticipated FOMC meeting, rate hike, and subsequent market reaction, this week is slated to be less eventful. The economic calendar is light and limited to second and third tier releases with the real attention getter the slate of Fed speakers. Five are scheduled to speak with three of those scheduled twice, so plenty of headlines are possible as they expound on their thinking about the hike from last week and what may lie ahead. Three of the five, John Williams, Beth Hammack, and Anna Paulson are voters this year so their opinions will carry a little more weight than the non-voting contingent of Thomas Barkin and Austin Goolsbee. Of course, with a light data calendar it leaves the field open for any headlines from the White House. Already there are signals/signs a renewed diplomatic effort may be afoot in the Middle East and that has oil down $3/bbl this morning. Alas we don’t use oil, we use refined products and those prices are staying elevated. Currently, the 10yr is yielding 4.9%, down 4bp, while the 2yr is yielding 4.72%, down 3bp on the day.
- As mentioned above, Fed Speak will be hot and heavy this week with five FOMC members slated to speak and three of those are voting members this year. While Warsh, Powell, and Waller are not scheduled to speak, Waller in particular could find his way to a microphone as he’s not shy about expressing his opinion on monetary matters, and that is even more so with a new chairman. Keep in mind the vote to hike last week was unanimous so we won’t hear any objections to the action, but the market will be keenly attuned to any hints or thoughts on the pace and number of hikes they think are necessary to return PCE to its 2% target.
- Away from Fed Speak, and we know we’re stretching to come up with content here, one of the more compelling data points will be the Wednesday release of the preliminary S&P Global PMI numbers for September. Recall last month the Manufacturing PMI printed at 53.9, Services at 56.5, and Composite at 56.0. With 50 being the dividing line between a contracting and expanding sector, the August results were clearly expansionary and that played out in most of the other August economic releases like payrolls and personal consumption/retail sales.
- Thursday brings the weekly jobless claims which have been trending lower to multi-month lows indicating the low-fire environment continues while hiring, at least in August, had a decided rebound as evidenced by the upbeat August payrolls report. However, one month does not make a trend, especially with the recent volatility, and subsequent material revisions in the payroll series so we take job market developments one month at a time.
- Also on Thursday, August New Home Sales will be released with an ever-so-slight pick-up in activity expected with sales forecasted to reach 615 thousand annualized vs. 607 thousand in July, or a 1.3% increase. Sales have been bouncing around the 600 thousand level for the last several years and well off the post-Covid spike of 1 million units sold as higher mortgage rates combined with little give in home prices will continue to make this sector a challenging one for the foreseeable future.
- The week finishes with the preliminary Durable Goods Orders for August with orders ex-transportation expected up 0.5% vs. 0.4% the prior month. The final University of Michigan Sentiment Survey results for September finish the week’s releases and we wait with bated breath to see if the dour preliminary results are revised even lower. Given this release’s connection with gas prices, and with those prices moving higher daily we suspect the preliminary readings could go even lower in the final. But as we always say about the consumer, it’s more about watching what they do (i.e., spend), and not so much what they say (pessimistic).
Odds for a Hike at Oct. FOMC Meeting – Coinflip 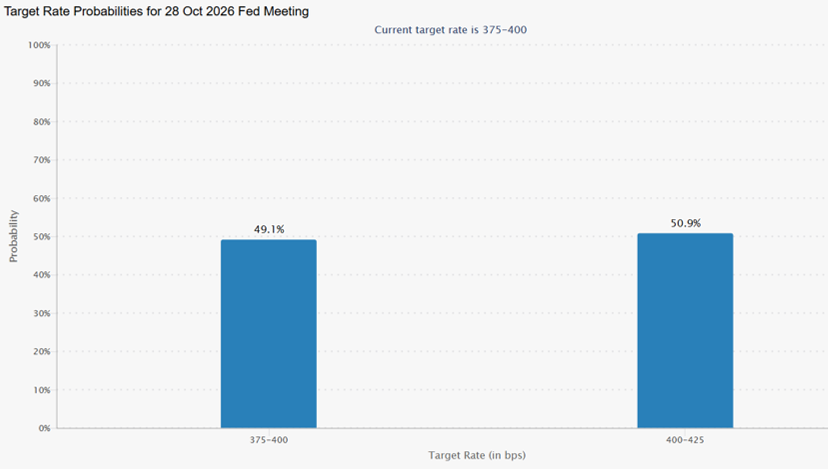
Source: CME Group
Prior to Last Week’s Rate Hike, Monetary Policy Seen as the Most Stimulative Since Sept. 2022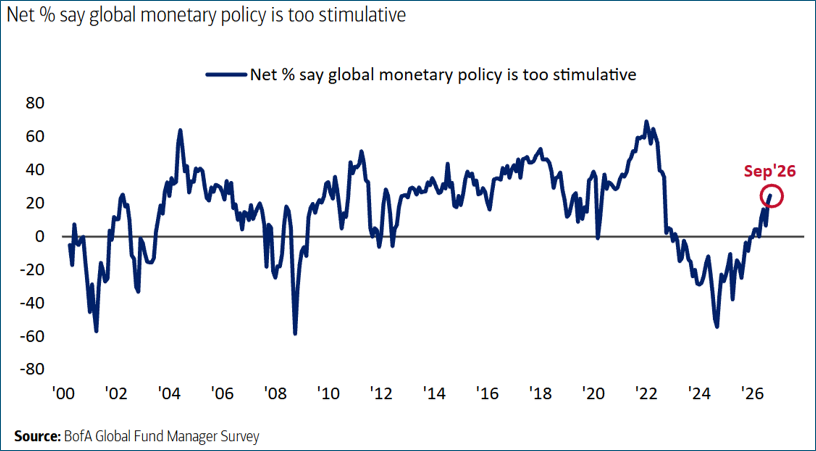 Source: BofA Global Fund Manager Survey
Bloomberg Financial Conditions Index Sees Loose Financial Conditions and One Hike Won’t Change That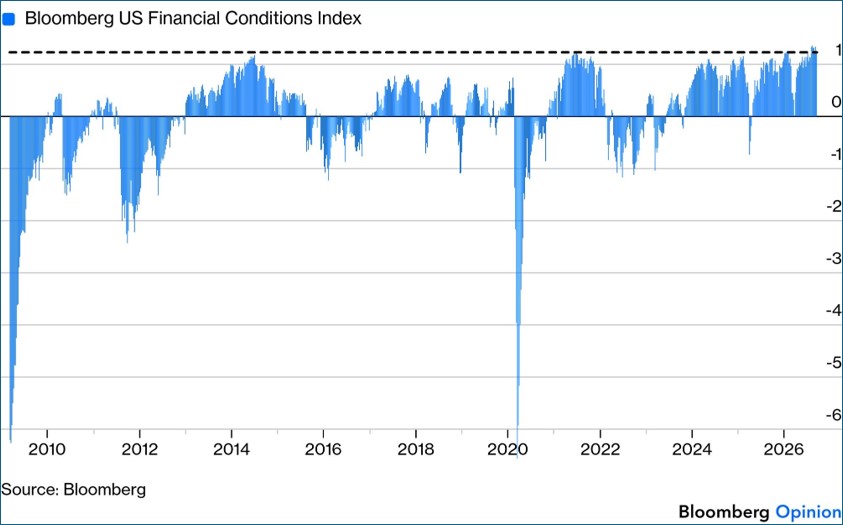 Source: Bloomberg
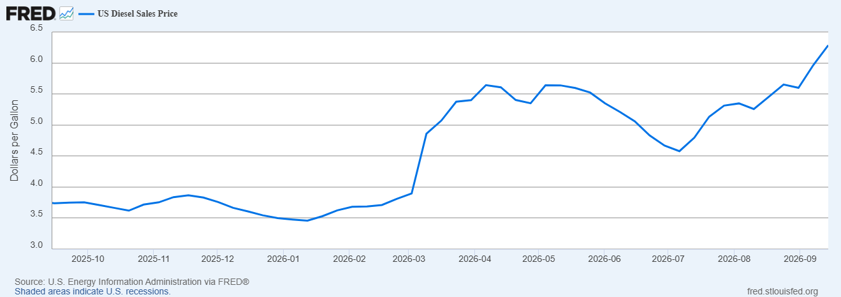
Forget Gas, Diesel Prices are 65% Higher Since February
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


