
Fed Expected to Keep Rates Unchanged Today
- With Fed speak talking down the possibility of a rate hike markets are expecting no change in today’s rate decision. The futures market sits at 9% chance for a hike, but that soars to nearly 86% when the calendar shifts to December. While a no-hike rate decision is mostly a foregone conclusion, hope springs eternal that Fed Chair Warsh will offer up expansive thoughts on where he sees policy headed. That last part is a wish that likely will go unfulfilled as Mr. Warsh has so far stuck to his stance of limited guidance and even limited rationale for the rate decision. In any event, we’ll get the statement and press conference this afternoon and hope to be surprised by an expansively articulate Fed Chair. Currently, the 10yr is yielding 5.00%, up 1bp, while the 2yr is yielding 4.75%, up 1bp on the day.
- The FOMC rate decision will be announced at 2pm ET but with odds of a rate hike at 9%, indicating little suspense regarding the decision. The curiosity will be how much is communicated via the statement and press conference regarding expectations for December. Fed Chair Warsh is wedded to his less-is-more style of communication so we’re not likely to hear much that will help assess a December rate decision, but with odds over 86% that there is a December hike not pushing back on that will be tacit approval that Warsh sees the one-sided odds as appropriate. The statement and press conference will be all that is produced at this meeting. A refreshed Summary of Economic Projections and dot plot of interest rates will have to wait until December.
- It should be noted too that after the September rate hike, the subsequent Warsh press conference was more a personal reflection of policy and not so much the Committee’s collective view which became apparent following the release of the meeting’s minutes. So, keep that in mind as you sift through the statement and presser today.
- As far as releases of note this week the preliminary Durable Goods Orders for September were released yesterday and were close to expectations, which was for an increase in orders and shipments versus a slow August. Orders increased 1.8% vs. 1.9% expected and went up from 0.1% in August. Capital goods shipments ex air and defense were similarly solid, growing 1.2% vs. 0.8% expected and 0.6% in August. So, nothing in the report indicates a sudden slowing and if anything, September represented a nice bounce in activity after a soft August.
- Also received yesterday was the Conference Board’s October read on consumer confidence. Overall sentiment improved to 91.7 vs. 81.0 expected and 84.2 in September. The Present Situation Index increased from 111.8 to 120.4, and the Expectations Index improved from 65.7 to 72.6. Fergus McCormick, Senior Economist for The Conference Board said that “Consumer confidence advanced in October, driven primarily by improved perceptions of current and expected business conditions. The recovery was in line with retail gasoline prices easing from September to October. Yet, despite the increase in October, consumer confidence remained on a long-term downward trend that’s persisted over the past few years. Consumers planned less spending on services and durable goods over the next six months. This likely reflected higher price levels and persistent inflation, which eroded consumers’ purchasing power.”
- The Present Situation Index rallied in October with the share saying conditions are “good” versus “bad” increasing by 4.8 percentage points to 3.6% following a notably negative reading last month. Perceptions of current employment conditions were moderately more favorable, with the labor market differential—the share of consumers saying jobs are “plentiful” minus the share saying jobs are “hard to get”—improving by 2.4 ppts to +5.3%. The Expectations Index was less pessimistic in October as all three of its components saw improvements.
- Tomorrow brings the Advance Goods Trade Balance for September with expectations of the goods deficit remaining wide at -$130.0 billion vs. -$132.6 billion in August. The AI buildout is doing the heavy lifting on the goods deficit as computer-related imports from Taiwan and China have been leading the goods deficit numbers wider for months and that’s likely to continue with September’s results.
Odds at 9% for Rate Hike Today 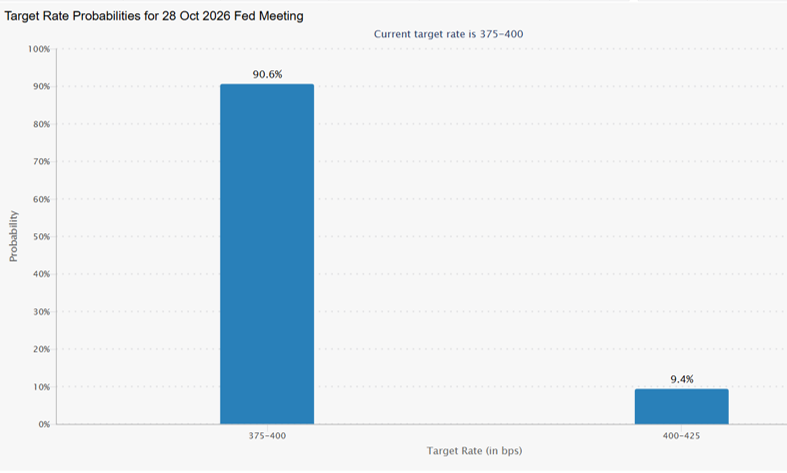 Source: CME Group
Consumer Confidence Improved in October but Remain Historically Low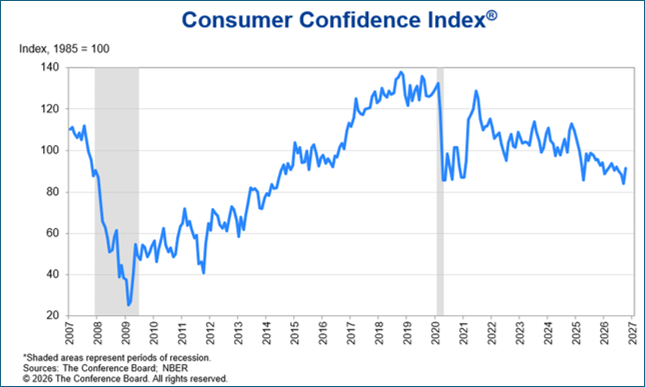 Source: The Conference Board
Consumers Expecting Higher Interest Rates Dipped Slightly in October but Remain Elevated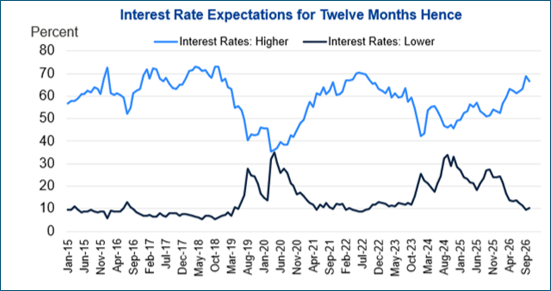 Source: The Conference Board
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


