
Fed Hikes 25bp and Expects Another by Year-End
Meeting Highlights
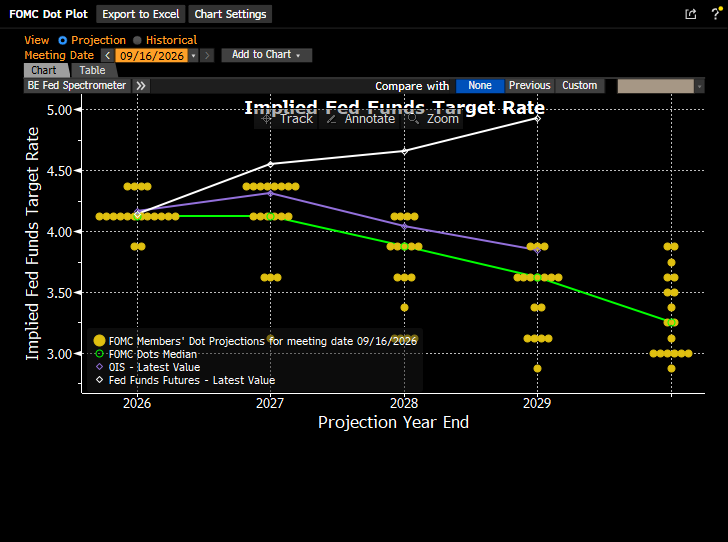
- As expected, the Fed raised the funds rate by 25bp resetting the target rate range to 3.75% – 4.00%. The biggest uncertainty heading into the meeting wasn’t the rate hike itself but the updated rate forecast, or dot plot. In June, they had the median funds rate for year-end 2026 at the pre-meeting level of 3.50% – 3.75%, implying no change at that time. Today, the 2026 year-end median rate is now 4.125%, implying a 4.00% – 4.25% range, or one more hike before year-end. The median then remains unchanged in 2027 before dipping in 2028 indicating an easing cycle.
- The Longer-Term dot, or the so-called neutral rate that is considered neither restrictive nor accommodative moved from 3.06% to 3.25%. If this were a true representation of the neutral rate, then the revised fed funds rate today would indicate more than 50bp of restrictive tightening. Many observers, however, believe the neutral rate is likely higher given the ongoing demand from the AI buildout that is driving much of today’s economic strength, indicating the degree of monetary tightness may not be nearly as significant as it appears with a low 3.25% estimate. The Fed historically makes only incremental changes to this estimate, but we think there is more to come in subsequent meetings, say a range of 3.25% to 3.50%. That would make the restrictive stance, even after today’s hike, less than it might appear.
- The notable change to the very brief statement is naturally related to the outlook on inflation. In the July statement the Committee was, “attentive to the risks to both sides of its dual mandate.” In today’s statement it was shortened to, “inflation remains elevated.” I guess the only thing to take from that is that inflation has the sole attention of the Fed right now as the labor market retains its stability.
- Fed Funds futures pricing prior to the announcement had 75% odds of two hikes by year-end 2026, including today’s hike. After the updated dot plot projections, that reflects a median of two hikes, the futures market odds for two hikes remained at 75%. Thus, the futures market expects the Fed to hike one more time over the last two meetings (Oct. or Dec.) before the calendar turns to 2027.
- Given this is a quarter-end meeting, the FOMC updated its economic forecast with a fresh Summary of Economic Projections (SEP). The Fed now sees 2026 GDP growth at 2.2% versus 2.4% in the June forecast. Growth is expected to slow to 2.3% in 2027 and 2.2% in 2028, both similar to the June forecast.
- On inflation, the Fed significantly increased the expected core PCE for year-end 2026 to 3.3% vs. 2.7% in the June forecast. We are currently at 3.4% as of July. The 2027 forecast was bumped three-tenths to 2.5% then 2.1% in 2028, a tenth higher than the June forecast.
- As for the labor market, the forecast is for the unemployment rate to remain at 4.3%, unchanged from the June forecast and matching the current unemployment rate. For 2027, the rate is expected to be 4.3% then 4.2% in 2028, again matching the June forecast.
- Today’s SEP update keeps in place most of the economic estimates forecast in the June SEP, except for the upward revisions to core PCE this year and next. Given the resilience of the economy and the ongoing energy shock, that’s a prudent approach. With the war dragging on longer than expected when hostilities commenced in February, the Committee is obviously alert to further pass through of elevated energy costs into the wider economy and the ongoing strength in AI capex which is keeping demand and price pressure elevated in non-energy areas. That combination will keep the Fed focused on its price stability mandate for the foreseeable future, especially with a stable labor market.
Dot Plot from September FOMC Meeting
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


