FOMC Rate Decision Highlights Upcoming Week
- The new week brings an FOMC meeting/rate decision on Wednesday where a hawkish pause is the overwhelming expectation. That said, while stock market gyrations are rarely mentioned in Fed communications, if the risk-off trade continues and/or spreads it will have implications for the economy and may complicate the Fed’s patient pause approach to inflation. Any financial tightening that comes because of an equity drawdown may not be enough by Wednesday to be reflected in the statement, or Warsh comments, but if the selling continues/spreads it will make a December rate hiking decision more difficult. Right now, hiking odds in the futures market don’t reflect that concern, but there remains a lot of time between now and the December 9th rate decision. It’s something to ponder as we wade through Fed communications this week and as attention turns to the year-end meeting. Currently, the 10yr is yielding 5.01%, up 2bp, while the 2yr is yielding 4.71%, up 3bp on the day.
- The FOMC rate decision on Wednesday is clearly the highlight of the week. Odds of a rate hike remain low at 10% but 82% that there is at least one rate hike by year end. The curiosity for this week’s meeting will be how much is communicated via the statement and press conference regarding expectations for December. Fed Chair Warsh seems wedded to his less-is-more style of communication so we’re not likely to hear any hints in assessing a December rate decision, but with odds where they are not pushing back will be tacit approval that he sees them as appropriate. In addition, it will be hard to remain completely non-committal after the latest inflation reports that were all on the warm side and could have easily been the basis for a rate hike this week if he were so inclined. Thus, keeping some inflation-fighting credibility will require more than being mute on the subject.
- While last week was light on economic data, the most important of the meager releases came mid-morning on Friday with the preliminary S&P Global PMI numbers for October. Recall last month the preliminary results were uniformly strong and that began a wave of Treasury selling with expectations of an October rate hike. The tone changed in subsequent weeks as Fed speak talked down those expectations. In any event, the October PMIs were not quite the upward shock that September delivered. The Manufacturing PMI printed at 55.8 vs. 55.9 in September, Services printed at 57.9 vs. 58.8 prior month and the Composite printed at 57.6 vs. 58.4. With 50 being the dividing line between a contracting and expanding sector the October results were the lowest in two months and more importantly did not build on the upward spike in September nonetheless they remained in solid expansionary territory. The slightly softer reads contributed to a quiet Treasury market as the week ended.
- The final October sentiment reading from the University of Michigan came late in the morning Friday and held mostly steady in October, registering a one-tenth dip below September (48.0 vs. 48.1). Increases in sentiment among Republicans and Democrats were balanced by declines among independents. The decline in the Current Conditions index (46.7 vs. 50.9) was driven entirely by buying conditions for durables, which plunged 18% because of higher interest rates and rising concerns about the affordability of such purchases. Purchasing power continues to dominate consumer views of the economy. Sentiment is now 10 percentage points below a year ago and 15 percentage points less than February, just prior to the Iran conflict.
- Year-ahead inflation expectations ticked up from 4.6% to 4.7% this month. The current reading substantially exceeds the 3.4% seen in February before the Iran conflict began, along with all 2024 readings. Long-run inflation expectations also stepped up from 3.4% in September to 3.5%, notably higher than their 2024 range of 2.8% to 3.2%. Inflation expectations over both time horizons increased for the second straight month to their highest readings since May.
- As far as releases of note this week they start with the preliminary Durable Goods Orders for September due tomorrow along with the Conference Board’s latest read on consumer confidence. The September Personal Income and Spending numbers with the PCE inflation series are due on Thursday. Expectations for PCE are 0.5% MoM and 3.6% YoY and core PCE of 0.3% MoM and 3.1% YoY.
- The first estimate of third quarter GDP will also be released Thursday with expectations of 3.0% annualized growth and PCE inflation at 3.5% annualized and core PCE inflation of 2.4% annualized. While the September personal income, spending and PCE inflation numbers will be a part of the GDP report, the biggest insight from the separate September report will be how well consumer spending and the PCE inflation numbers behaved as the quarter ended. So, stay tuned after the Wednesday FOMC meeting as important info will be forthcoming on Thursday.
Odds at 10% for Rate Hike This Week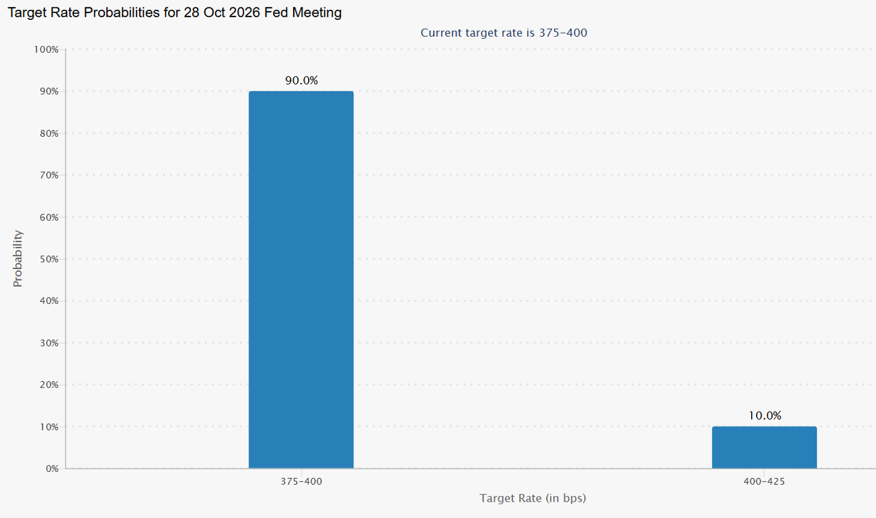
Source: CME Group
Odds at 82% That At Least One Hike Happens Before Year-End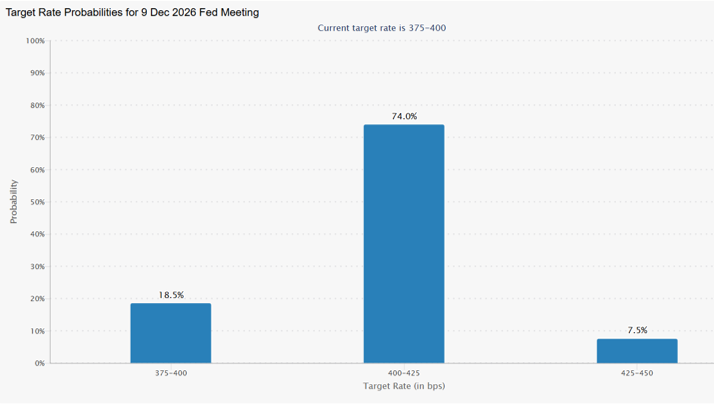 Source: CME Group
S&P Global Composite Pricing Points to Continued Inflation Pressure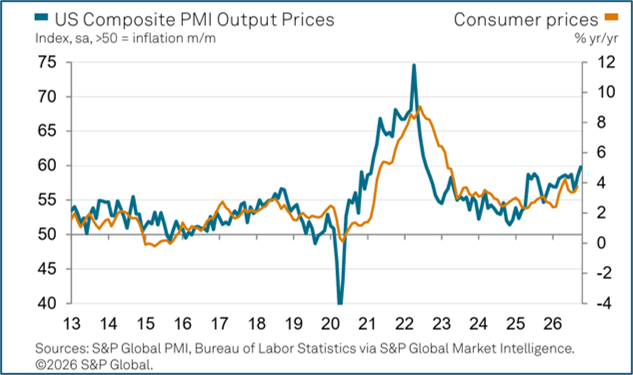 Source: S&P Global
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


