Jobs Week Spars with War News for Market Attention
- After last week’s rather light, but eventful calendar, this week provides a bevy of first-tier reports headlined by the September jobs report on Friday, the Fed’s preferred inflation reading and an update to 2nd quarter GDP on Wednesday. It must be said, however, that with inflation the current focus of the Fed, price pressure is clearly driving the hike/no hike bus right now. And with the weekend news that a ceasefire in the Middle East remains out of reach, oil prices and Treasury yields are higher as we start the week. So, the data flow will be heavy but not so impactful unless we get a surprise from the August jobs report on Friday. The data flow starts tomorrow with the JOLT Survey. We discuss some of those highlights below. Currently, the 10yr is yielding 5.21%, up 3bp on the day, while the 2yr is yielding 4.91%, up 4bp on the day.
- First up will be the Conference Board’s latest consumer sentiment readings for September due on Tuesday. Recall the University of Michigan’s latest sentiment read was another disappointing report as higher gas prices dimmed consumer outlooks in that report. Expectations for this one are for a slight increase in sentiment from 89.4 to 91.0. This report has less of a direct connection to gas prices than the Univ. of Michigan version so it may provide a “cleaner” read on sentiment. Regardless of which sentiment report you prefer, they have all been quite negative for some time, but consumer spending hasn’t suffered with the dour outlooks. Just a reminder to watch what the consumer does and not so much what they say.
- The Job Openings and Labor Turnover Survey for August will also arrive tomorrow. Job openings are expected to slip slightly from 7.271 million to 7.225 million, keeping it near 1-to-1 with the number of unemployed. At the peak of labor market tightness coming out of Covid openings rose over 12 million, so the slide since then is another indication of the labor market working off overheated demand to something closer to equilibrium. The sub-indices like the Quits Rate (1.9% in July), and Layoff Rate (1.0%) will provide another view of the labor market to see if there is any uptick in layoffs and/or slide in worker confidence in finding another job. Given the recent rebound in some employment-related PMI readings we’ll see if that uptick was evident in these August numbers.
- Wednesday brings the Fed’s preferred inflation measures, PCE, for August. It’s the last of the August inflation numbers and will be one of the key reports when the FOMC convenes next month to ponder a possible rate hike. Expectations are for overall PCE inflation to increase 0.4% MoM vs. 0.2% prior month and 3.7% YoY, same as July. Core PCE is expected to have increased 0.3% MoM vs. 0.2% prior month and 3.4% YoY vs. 3.3% in July. If those numbers are realized it will add to odds for an October hike, especially the 0.3% monthly gain in core PCE as it will lead to an uptick in the YoY rate. There will be adjustments to a few categories such as portfolio management fees, legal services and computer software and services that should lower the YoY rate approximately 20bp. Given the current 3.3% rate, that adjustment will help the inflation-fighting story but only at the margins.
- The same report carries with it August personal income and spending numbers. Incomes are expected to have increased 0.4%, same as July, while spending is expected to surge 0.8% vs. 0.2% the prior month. Spending adjusted for inflation is expected to have risen a solid 0.5% vs. July’s 0.0% reading. Those figures, if realized, point to a decent month of income and even better consumption that confirms the solid spending in the previously released retail sales report. Solid spending as evidenced by this most comprehensive of consumption reports will add to the hiking odds in October.
- After the last of the August reports wander in, the data turns to September with ISM Manufacturing on Thursday, and after the upward spike in activity revealed in S&P’s version, investors will be keen to see if it is confirmed with the more well-known ISM series. Expectations are for the headline survey to change little from 54.6 to 55.0, indicating continuing solid expansion in the manufacturing sector. The sub-indices like Prices Paid (71.1 in August), New Orders (53.7) and Employment (51.2) will be scrutinized as well.
- On Friday, September Nonfarm Payrolls are expected to report 104 thousand new jobs vs. 162 thousand in the surprisingly strong August report. Private payrolls are expected to increase 90 thousand vs. 127 thousand in August and the unemployment rate is expected to increase a tenth to 4.2% as some labor force growth returns with not all new entrants finding immediate employment. Average hourly earnings are expected to go up 0.3% MoM vs. 0.2% prior month while annual earnings are expected to improve modestly from 3.1% to 3.3%. That last figure could also be pivotal in assessing whether the Fed will hike in October. If wage growth reaccelerates like expected, and flagged in other recent reports, it could also add to the hiking case as wage gains add to the price pressure from supply shocks.
Odds for Hike in October – Moving Higher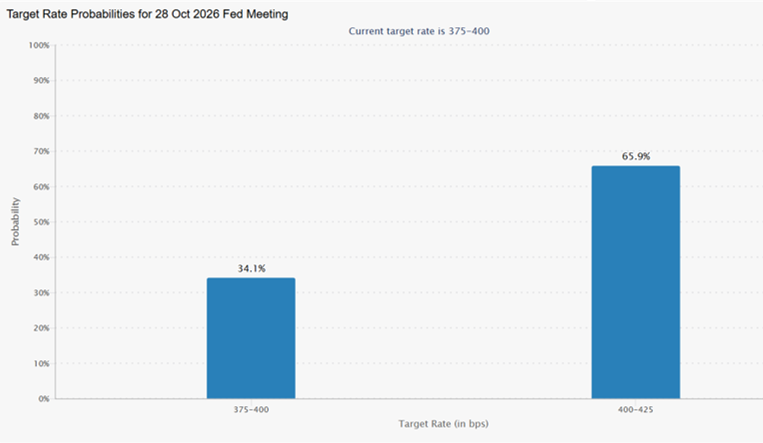 Source: CME Group
September Job Gains Expected to be a Solid 104k but less than August’s Surprisingly Strong 162K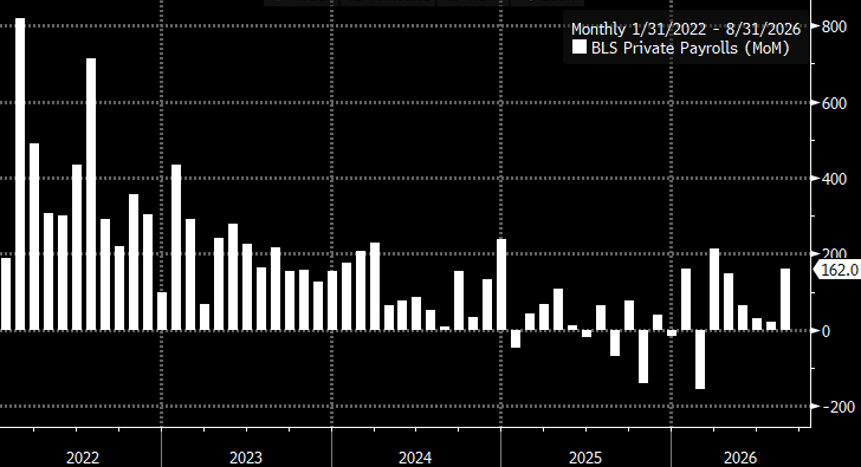 Source: BLS
Average Hourly Earnings (YoY) – After a Long Downtrend Does this Turn Higher?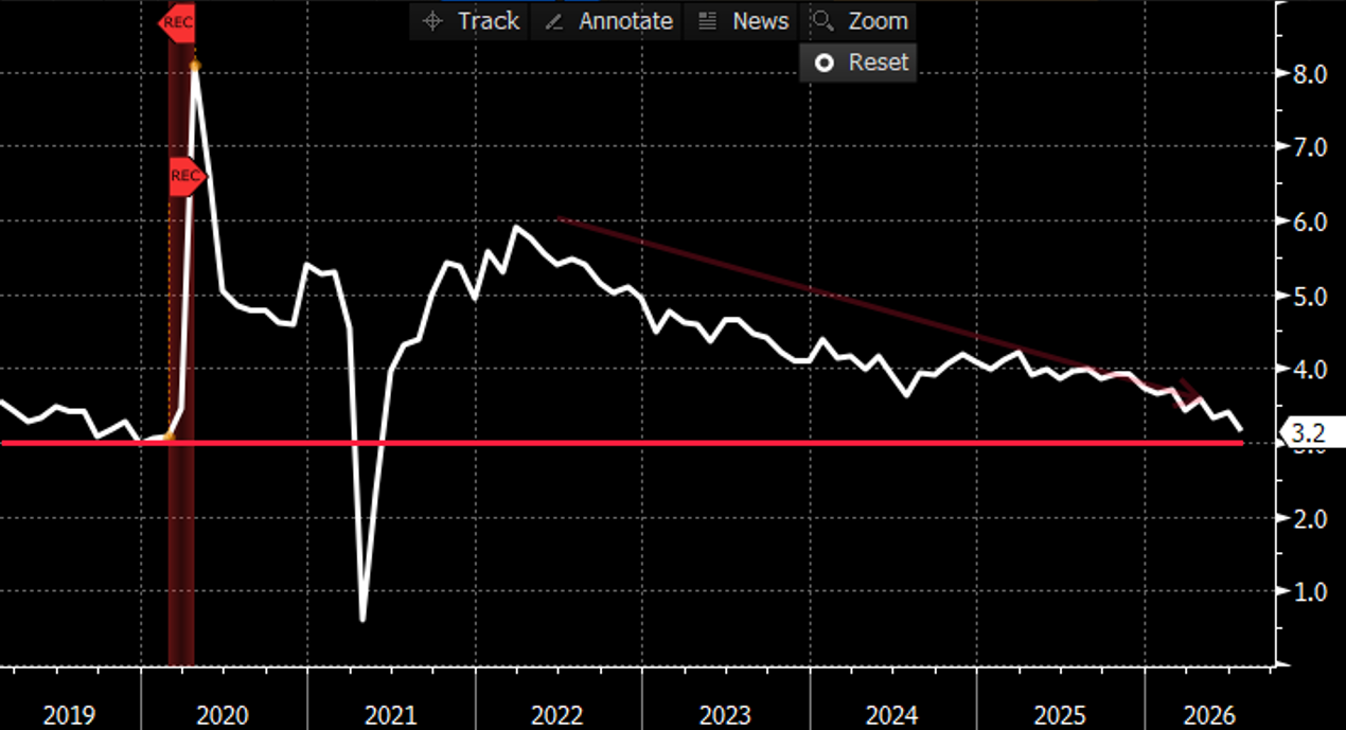 Source: BLS
September ISMs Expected to Build on August’s Expansion Signal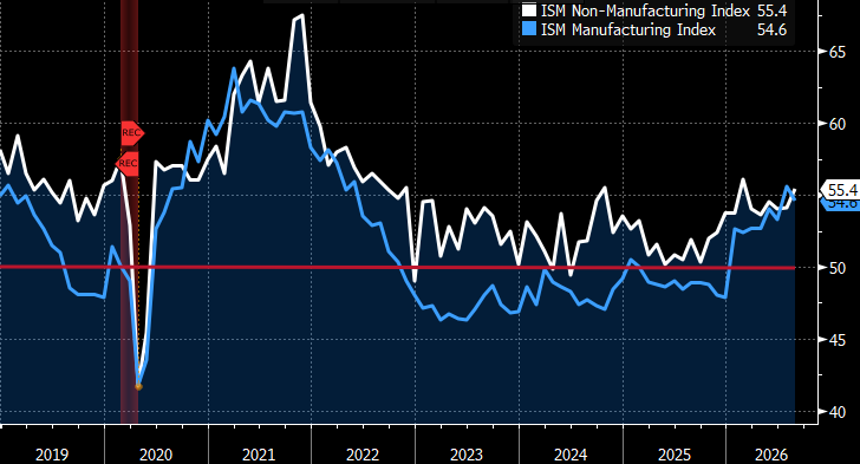 Source: ISM
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


