September Core CPI – Hotter than Expected with Odds to Hike around 44%
- September inflation data began arriving today with CPI this morning. Results are discussed in more detail below but suffice it to say the monthly core rate rose 0.3% vs. 0.2% expected with odds of an October rate hike around 44%. Odds were under 20% prior to the report. Fed speak since that FOMC meeting and the minutes conveyed the view that the September rate hike was more a “risk management” tweak than the start of a new hiking cycle, with the Fed content to wait on new data before hiking again. So, while inflation data has been the key force driving the rate/pause decision, the consensus view of Fed thinking after the September meeting is one of less urgency than the Warsh post-FOMC meeting statements implied. That will be an issue going forward as markets assess the Chair’s statements that may reflect his view rather than the committee’s. Thus, the communication conundrum under a Warsh Fed seems likely to continue. Currently, the 10yr is yielding 5.32%, up 10bp, while the 2yr is yielding 4.93%, up 13bp on the day.
- Today’s September CPI was hotter than expected with odds of an October rate hike moving from around 20% prior to 44% following the inflation numbers. Headline inflation was up 0.6% for the month, as expected, but up from the 0.4% August increase. The YoY rate increased from 3.4% to 3.7%, a tenth higher than expected. Energy costs were up 5.2% for the month vs. 2.1% in August as the on-again/off-again ceasefire talks were more off in September leading to higher energy costs. The Food category, however, was docile yet again, this time unchanged following two months of 0.1% increases.
- Core CPI increased 0.3% MoM (0.33% unrounded), a tenth hotter than the 0.2% expected but matching August’s core print. With the 3% increase in the core rate the YoY rate increased from 2.4% to 2.6%, also a tenth higher than expectations and effectively reversing the August improvement which was the lowest core YoY reading since March 2021. As we mentioned last month, the YoY improvement gets harder as a string of 0.2% monthly prints from 2025 roll off in the fourth quarter and that contributed to the two-tenths uptick in September. Shelter costs rose 0.4%, up from August’s 0.3% increase and that followed two months at 0.1% which was the smallest Shelter print since January 2021. The increase here was driven primarily by lodging expense increasing 2.0% and that followed a 2.4% increase in August.
- A critical piece of Shelter cost, Owners’ Equivalent Rent (OER), rose 0.3%, a tenth higher than the August increase. In eight of the last nine months OER has ranged between 0.2% and 0.3% MoM. Pre-pandemic, OER – the largest single CPI component – also ranged between 0.2% and 0.3%. Getting OER to consistently print closer to 0.2%, or below, remains one of the keys for getting back to the 2% target. Core Services ex-Housing (aka Super Core) followed a spikey 0.5% August increase, the highest since January, with a still hot 0.4% in September and the three-month annual average is 4.6%. The slight moderation from August will be noted by FOMC members but if it remains in this range it sets the stage for a December rate hike.
- Tomorrow brings us September PPI and combined with today’s CPI allows analysts to refine their PCE inflation estimates numbers due at the end of the month. PPI is expected to increase 0.6% vs. 0.4% in August with PPI ex-food and energy up 0.3% vs. 0.2% prior month. PPI ex-food, energy, and trade is also expected up 0.3%, matching the August increase. YoY levels are not expected to improve much with the headline measure matching August at 5.4%, and ex-food, energy, and trade at 4.7%, also unchanged from August. The final piece that fits into PCE comes on Friday with the September Import/Export Price report.
- As we mentioned last month, the quest to reach 2% PCE inflation will be extremely challenging. The Middle East unrest is not going away anytime soon and the longer it drags on the more higher energy costs spread into other non-energy sectors. Also, we believe companies that have resisted price hikes this year will be looking to correct that in January with new year price adjustments. Also, with modest comps from last year’s fourth quarter limiting potential YoY improvement, and the expected new year price hikes, 2027 first quarter may force the Fed back into a more aggressive hiking mode. Thus, we see the potential for first and second quarter rate hikes, especially if the economy remains solid and employment holds up, which we expect.
- Tomorrow we also get a look at September consumer spending with the Advance Retail Sales Report. Sales are expected to be decent but off the robust August print. Headline sales are expected up 0.3% MoM vs. 1.1% in August. Sales ex autos and gas are expected up 0.2% MoM vs. 1.1% prior month. The core spending category, the so-called Control Group, is expected up 0.3% MoM vs. 1.2% which was the largest gain since September 2024. Keep in mind that this report is not inflation adjusted and given the uptick in energy prices during the month the real spending levels were even more modest. That said, the consumer has defied previous proclamations of their imminent demise, so we’ll consider the modest expectations more a temporary break in breakneck spending rather than a more troubling change in trend. In any event, if the actual numbers meet expectations, it fits well with the forecasted pause at the October FOMC meeting on the 28th.
Odds for an October Hike Jump from 20% to 44%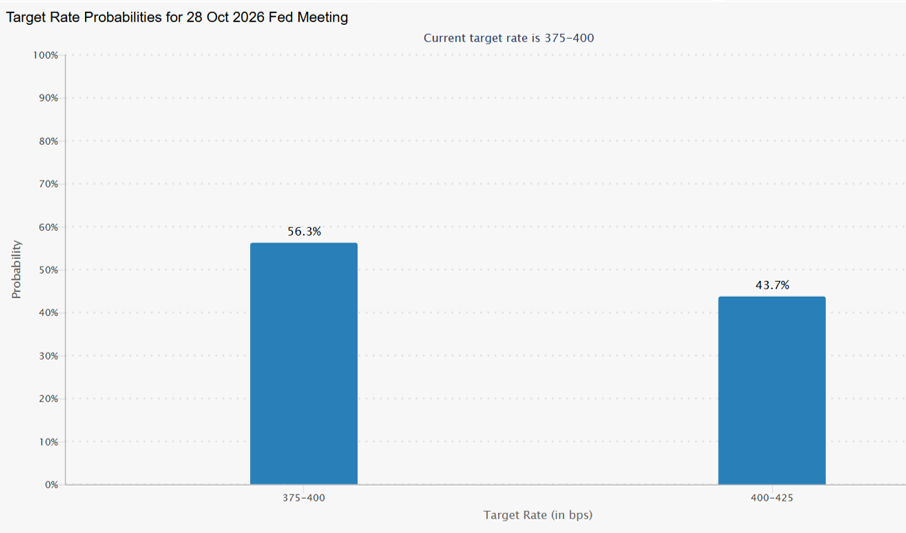 Source: CME Group
September CPI MoM – Hotter on Core as Shelter and SuperCore Drive Increase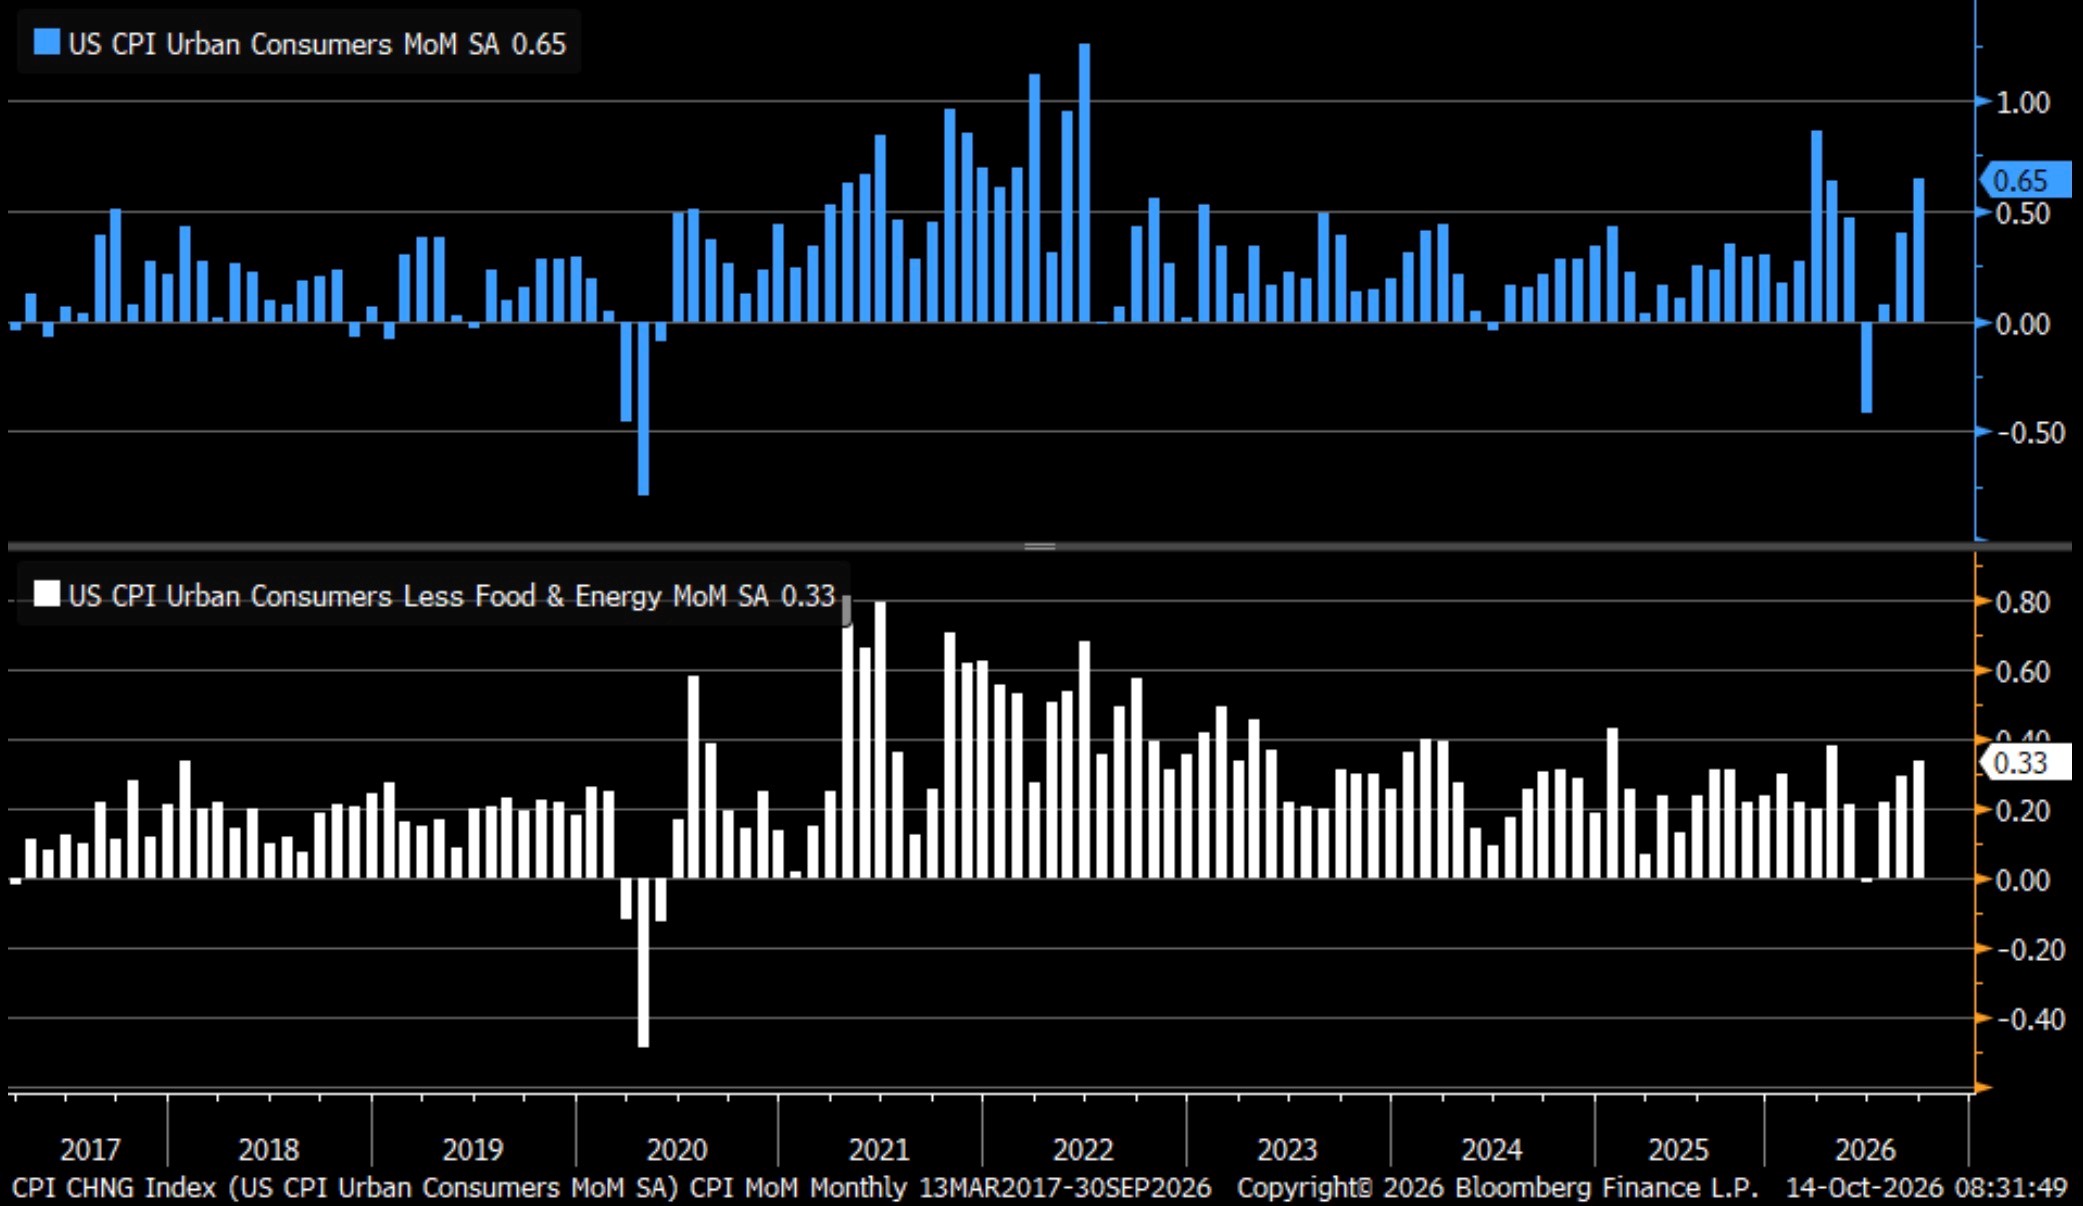 Source: BLS
Monthly Price Changes by Category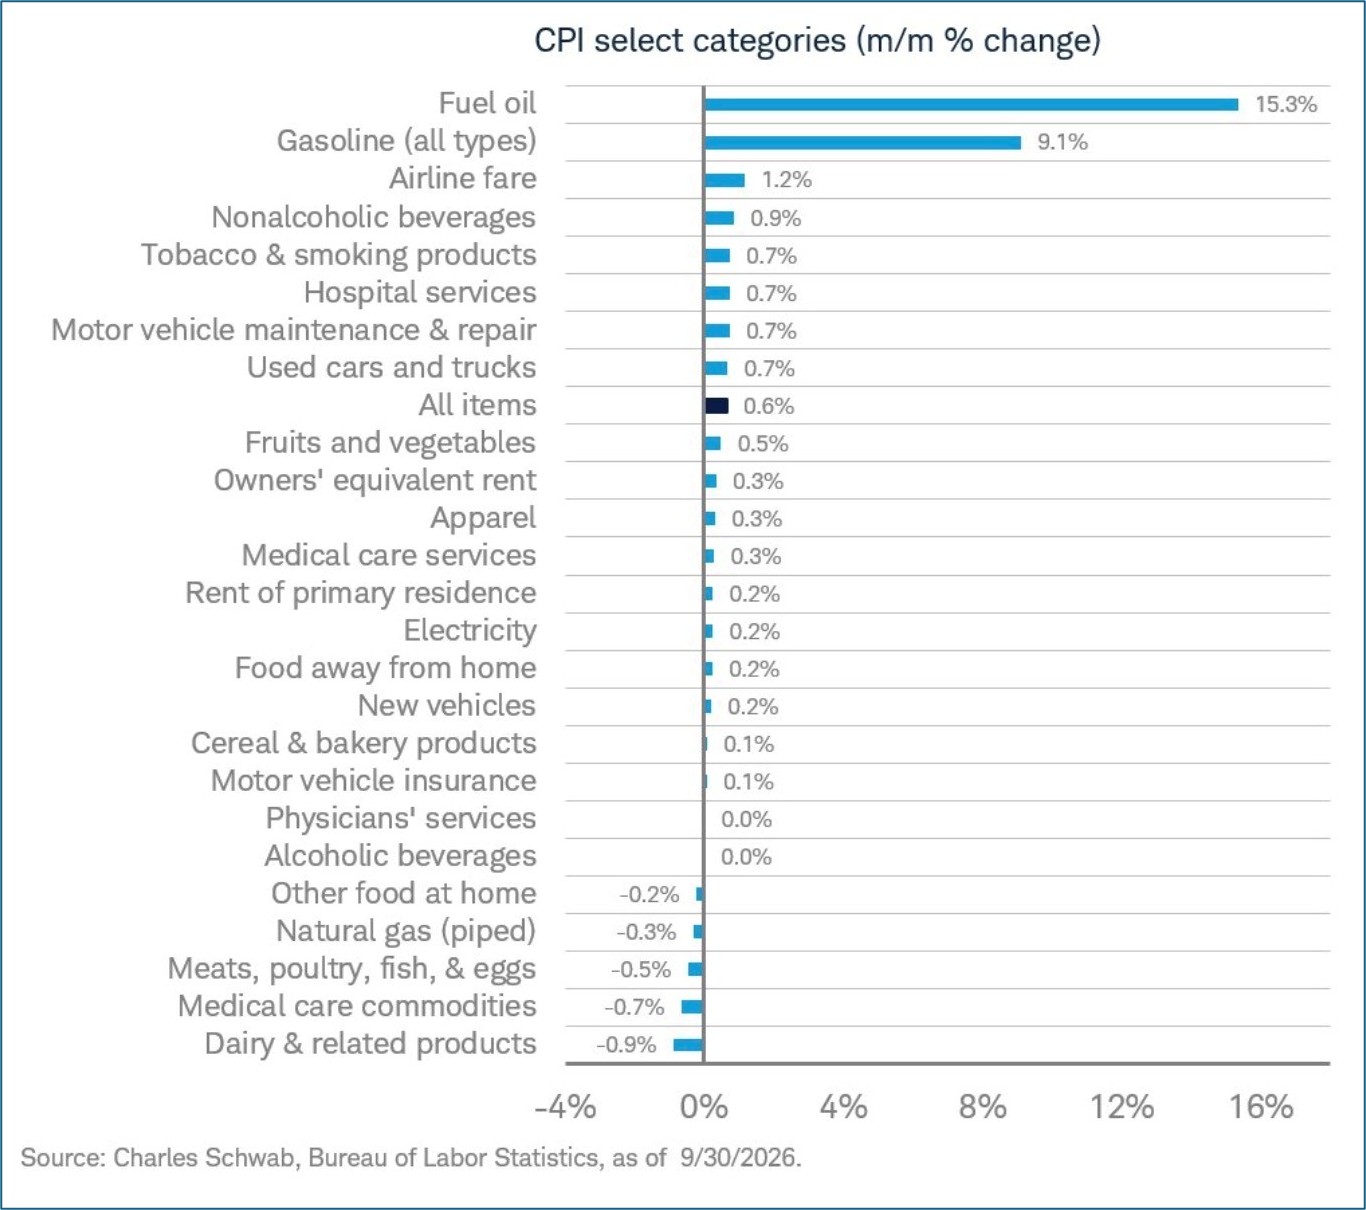 Source: BLS
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


