Slow Data Week Allows for Pondering When Next Rate Hike Occurs
- While the mediocre September jobs report still allows the Fed to focus on its price stability mandate when it meets later this month, the stable labor market that was touted after August’s surprising strength might be on thinner ice than it appeared a month ago. Thus, it provides one reason for the Fed to wait on another rate hike until December. The economic calendar is lighter this week and truth be told, the key report left before the October 28 FOMC meeting will be the Sept. CPI report due next week on October 14th. As we sit here today, however, it would have to be extremely hot to shift the Fed back into hiking mode, as odds for a hike sit at only 19%. Currently, the 10yr is yielding 5.27%, unchanged on the day, while the 2yr is yielding 4.81% up 2bp on the day.
- If you remember the week before last, the preliminary S&P Global PMI series for September was released and it revealed surprising strength in both the manufacturing and services sectors. That contributed to another round of Treasury selling as it implied the Fed would be hiking. That thought has receded quite a bit, especially after the jobs report and soothing “what’s the hurry” comments from more than one Fed official. In any event, the final numbers for that report will be updated at 9:45am ET and we’ll see if that early strength is repeated in the final numbers.
- This morning also brings the ISM Services PMI Index. Expectations are for a 55.2 print on the headline number vs. 55.4 in August. As usual, the Prices Paid (73.0 expected vs. 72.6 in Aug.), New Orders (60.1 exp. vs. 60.9 Aug.), and Employment (49.0 exp. vs. 47.8 Aug.) will garner plenty of eyes as well. As you can see from the August print to expectations prices paid and employment are expected slightly higher while orders slip a bit but if the actual numbers are close to expectations, it will be a shoulder shrug kind of report.
- Tomorrow, the August Trade Balance will be released with an expected deficit of -$83.8 billion. This includes both goods and services and with the goods deficit reaching -$120 billion from a previously released report, it was the widest deficit since April last year when the Liberation Day announcement set off a flurry of rushed import orders to beat the coming tariffs. That goods deficit is being driven wider by AI-related imports of chips and other network/data gear and is just another example of the numerous fingerprints the AI buildout is having on our economy.
- On Wednesday, the FOMC Minutes from the Sept. 19 meeting will be released. As mentioned above, the weaker than expected jobs report may dent some of the labor market stability thoughts, so we’ll see how heavily Fed officials relied on that in the discussion to hike. In any event, with some of the soothing Fed speak combined with the disappointing jobs report, the market has totally moved thoughts of an October rate hike into December. October rate hiking odds have moved down from over 70% to 19% this morning. Odds for a December hike stand at 68% with another 15% betting it’s two hikes by year-end.
- Also, the Treasury will be auctioning three coupon-bearing issues this week with $58 billion in 3yr notes tomorrow, $39 billion in 10yr notes Wednesday, and $22 billion in 30yr bonds on Thursday. Given the global angst over fiscal concerns with rising yields being one consequence, it will be informative to see how well the auctions go. With Treasury yields at or near 20yr highs one would expect an easy reception. If it’s not, that means global concerns still persist at these elevated yield levels.
- Finally, the preliminary University of Michigan Sentiment Survey for October will be released on Friday. Recall that in August, overall sentiment fell to 51.7 from 55.2 with expectations for a slight tick lower to 51.0. While overall sentiment has been moving lower, driven in large part by gas and the affordability issue, the Fed wants inflation expectations “well anchored,” and year-ahead inflation expectations will be a key reading with September’s at 4.6% vs. 4.2% the prior month and that’s up from 4.0% in July. With gas and diesel prices remaining elevated it’s not expected that much if any improvement will be found in the update. The Fed has assuaged some of the angst over that inflation expectation creeping higher by mentioning that market-based measures, like the TIPS inflation breakeven (see graph below), have been more stable, but even here they are creeping higher as well, at least the 1yr. While this alone wouldn’t push the Fed from a pause into a hike, it might arouse some dissents from the more price conscious officials.
October Rate Hiking Odds Continue to Head Lower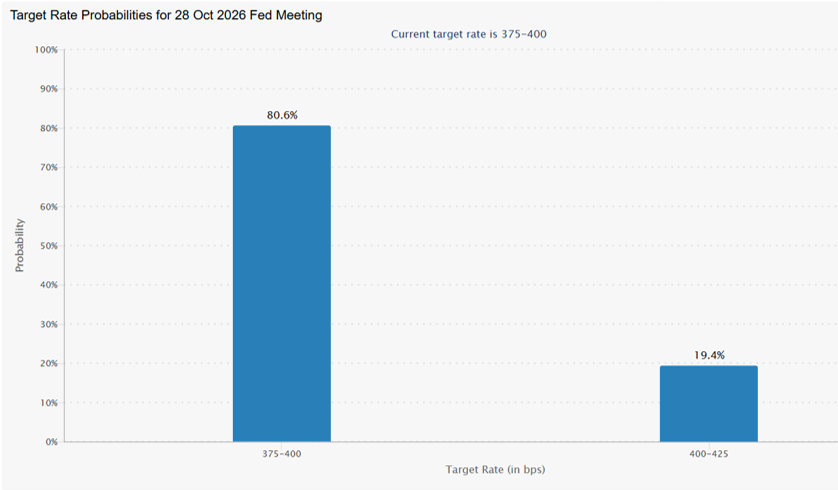 Source: CME Group
If the Fed Pauses in October, Odds Say a December Hike Likely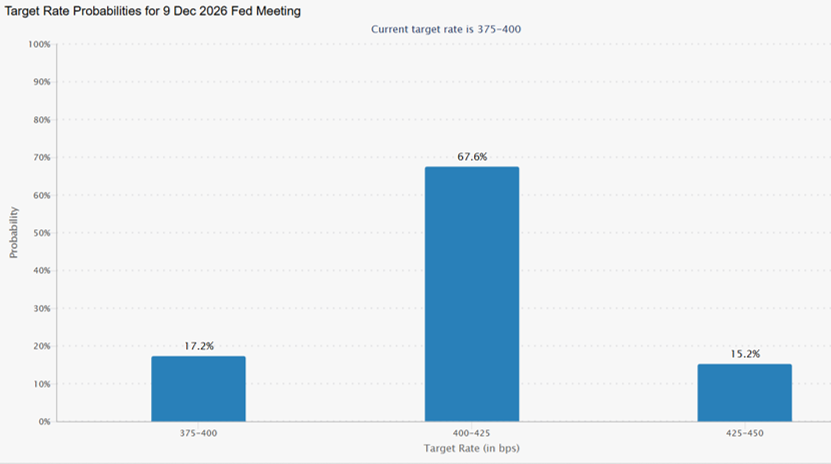 Source: CME Group
TIPS Inflation Breakeven Rates – 1yr Creeping Higher, 5yr & 10yr Stable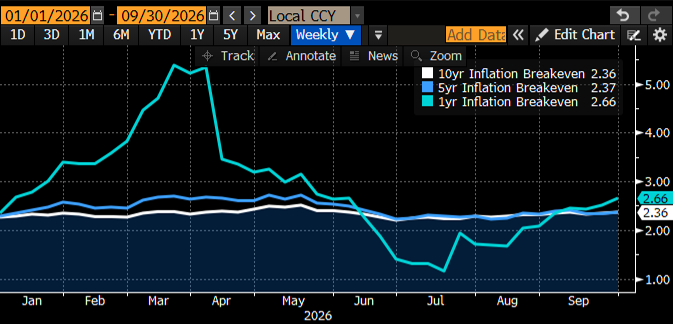 Source: Bloomberg
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


