
Will the Warsh Fed Follow Tough Talk with Action?
- Now that we’ve safely navigated the latest inflation readings for August, the stage is set for the FOMC to deliver what the market widely expects will be a rate hike. Interestingly, the market took that slightly hotter core CPI reading, and the surge in rate hiking odds, and rallied equities while the long end remained in place, but short-end yields continued to lift in anticipation of a hike. While the highlight of the week will surely be the FOMC rate decision on Wednesday, we’ll also get one more August inflation report that day (Import/Export Prices) and retail sales as our monthly assessment of the consumer begins anew. We’ll discuss those topics in more detail below. With a lack of Middle East progress over the weekend, oil is higher with WTI back over $100/bbl and that has equities on the back foot as we open the week. Currently, the 10yr is yielding 4.98%, up 1bp, while the 2yr is yielding 4.64%, unchanged on the day.
- Friday’s CPI release was near expectations, but core came in a touch hot at 0.3% MoM (0.29% unrounded) vs. 0.2% expected. Despite the 3% monthly increase the YoY rate decreased from 2.5% to 2.4%, which did match expectations. While it’s the lowest core YoY reading since March 2021, the improvement from here gets harder as a string of 0.2% monthly prints from 2025 roll off in the fourth quarter. Also, shelter costs rose 0.3% after two months at 0.1%. The increase here was driven primarily by lodging expenses surging by 2.4% while the always important component of Shelter cost, Owners’ Equivalent Rent (OER), remained somewhat docile at 0.2%, which was an improvement from July’s 0.3% increase. However, Core Services ex-Housing (aka Super Core) followed a modest July 0.19% increase spiking 0.51%, the highest reading since January and the YoY rate increased from 2.84% to 3.00%. That is probably a bridge too far for the pause camp, and after Warsh’s hawkish tone at Jackson Hole a pause would be hardto explain away, thus, the increased odds of hiking look right to us.
- While the FOMC meeting will be consequential enough with a pending hiking cycle looking to commence once again, the meeting will also provide a refresh on the SEP (Summary of Economic Projections) along with the Dot Plot of expected Fed Fund rates over the next several years. The year-end 2026 dots will be illuminating as well as the 2027 dots. As the market shifts from an expected Wednesday hike, the question moves to how many will follow? Right now, futures are at 76% that see two or more hikes by year-end. (49% at 2 hikes total, and 27% at 3 hikes). Looking past December, odds for more than three hikes increase some but are not appreciably greater. Thus, futures see three hikes as close to a done deal and are open minded about adding a fourth if necessary.
- With rate hikes now looking more likely, the question shifts to will they be effective in bringing down inflation? Part of the upward move in long rates has been the lack of Fed action. Thus, with the increased odds of a hike, 10yr yields were nearly unchanged on Friday. A hike on Wednesday, followed by a messaging of more to come will likely induce a long-end rally as the market realizes the Fed is not all talk. The AI buildout, however, will continue and the price pressure and demand that places on the economy will not be impacted by a 25bp rate hike. Thus, with that source of price pressure still in place, and if the energy shock continues, inflation numbers are not likely to show dramatic improvement. The messaging, however, will be a new input into the bond market calculus that has been missing to date.
- With the FOMC meeting taking up most of the oxygen this week, we do get an important read on the health of the consumer with the August Retail Sales report on Wednesday morning. Expectations are for a rebound in spending after a lackluster July. Advance retail sales are expected to increase 0.9% vs. -0.6% in July. Sales ex autos and gas are expected to be up 0.4% vs. -0.2% and the control group that represents core spending is expected up 0.4% vs. -0.4% prior month. Thus, a nice bounce back after a concerning downturn in July is the expectation. If it comes to be, that will once again highlight the folly of predicting the demise of the US consumer.
- Juxtaposed against the expected upbeat retail sales numbers, the preliminary University of Michigan Sentiment Survey for September was released late Friday morning and sentiment measures took a hard fall as energy prices resumed their upward move in August and early September. Overall sentiment fell to 47.8 from 51.7. If that preliminary level holds it will be second lowest in the decades-long history of the index. Current Conditions slipped a bit lower to 50.9 vs. 51.9 but Expectations took a real header to 45.8 vs. 51.5. With the uptick in gas prices in August and early September, it’s not surprising to see the sentiment measures decline as this series is closely linked to gas prices versus some of the other consumer sentiment measures. We take note of the declining sentiment measures but at the same time see retail sales expected to rebound. Once again, it’s probably more important to take what the consumer does over what they say. Or it’s an example of the K-shaped economy continuing to motor along with the well-heeled shoppers continuing to carry the load at present.
- Unsurprisingly, Inflation expectations from the same report moved higher as well. The year-ahead inflation expectation increased to 4.6%, from 4.0% in July. In February, before the war, year ahead inflation expectations were 3.4%, and 2025 readings were in the 2.3% – 3.0% range. Long-run (5-10yrs) inflation expectations increased to 3.4% from 3.3%. That broke a three-month streak at the lower level. In 2025, values ranged between 2.8% and 3.2%, while in 2019-2020, they were consistently below 2.8%. So, inflation expectations ticked higher after a couple months of holding steady and remained above pre-war levels. That will be another item noted by the FOMC Inflation Hawks.
Odds for Hikes by Year-End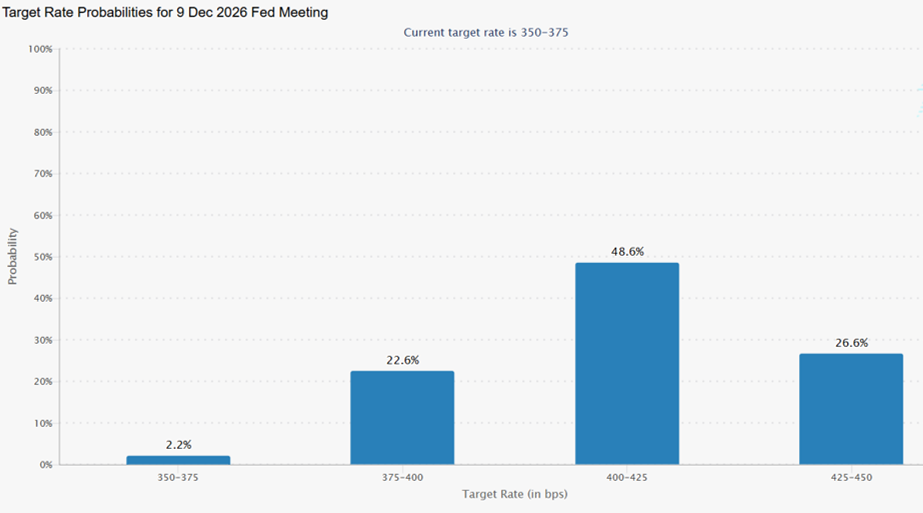 Source: CME Group
Street Forecasts Prior to Last Friday’s CPI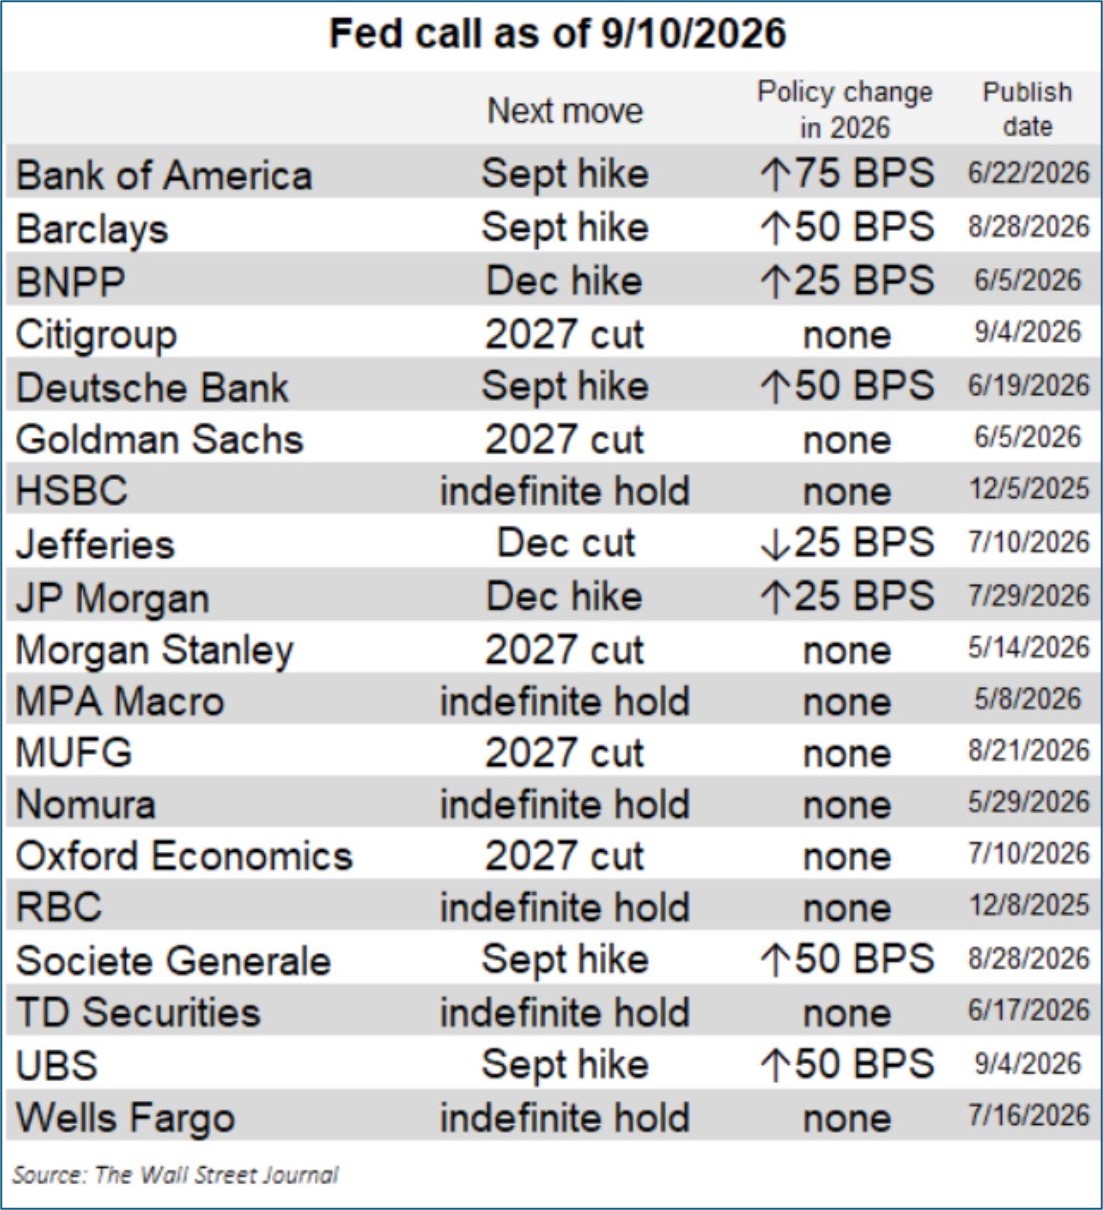 Source: Wall Street Journal
West Texas Intermediate Oil Back Over $100/bbl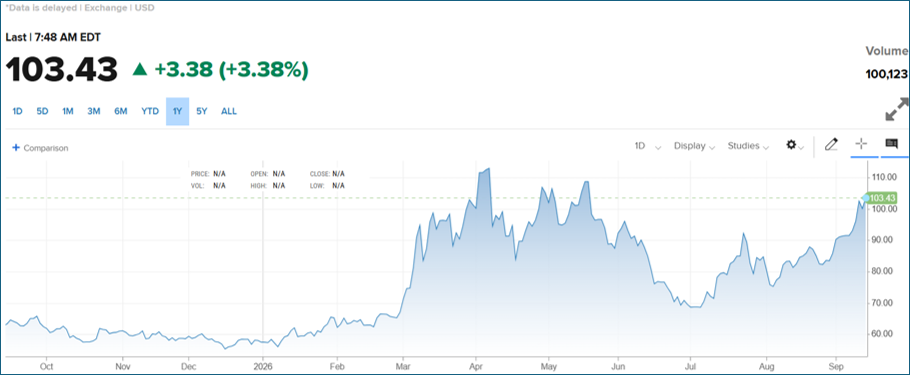 Source: CME Group
The Increase in Sovereign Yields is a Global Thing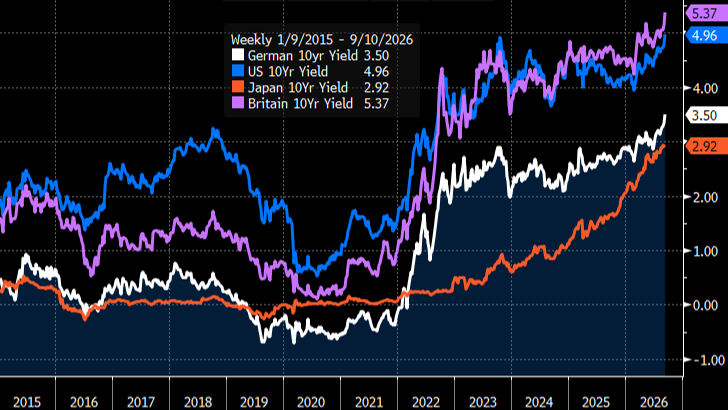 Source: Bloomberg
Securities offered through the SouthState | DuncanWilliams 1) are not FDIC insured, 2) not guaranteed by any bank, and 3) may lose value including a possible loss of principal invested. SouthState | DuncanWilliams does not provide legal or tax advice. Recipients should consult with their own legal or tax professionals prior to making any decision with a legal or tax consequence. The information contained in the summary was obtained from various sources that SouthState | DuncanWilliams believes to be reliable, but we do not guarantee its accuracy or completeness. The information contained in the summary speaks only to the dates shown and is subject to change with notice. This summary is for informational purposes only and is not intended to provide a recommendation with respect to any security. In addition, this summary does not take into account the financial position or investment objectives of any specific investor. This is not an offer to sell or buy any securities product, nor should it be construed as investment advice or investment recommendations.


